SFL (SFL) Locks In $750 Million Hapag-Lloyd Deal, Backlog Hits $4.6 Billion
SFL Corporation Ltd. (NYSE:SFL) locked in a charter extension with Hapag-Lloyd AG for another seven years, covering six 15,400 TEU container vessels. Backed...
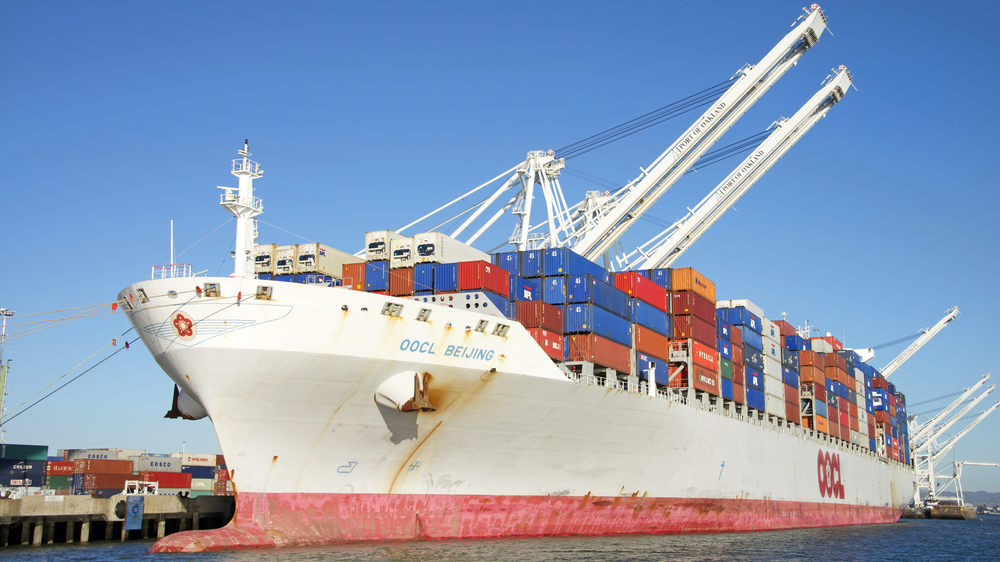
SFL Corporation Ltd. (NYSE: SFL ) locked in a charter extension with Hapag-Lloyd AG for another seven years, covering six 15,400 TEU container vessels. Backed by ongoing strength across the container segment, the vessels will stay under firm rates with charter coverage through 2035-36. This development builds on the company's prevailing expansion momentum in 2026, having already added over $1 billion to its charter backlog through long-term arrangements.
For SFL, this charter extension adds up to a robust topline visibility, as the company's growing backlog could convert into steady revenues up until mid-2030s. It also deepens the company's long-standing ties with a highly regarded customer, ranked as the fifth-largest container shipping line globally. The agreement strengthens SFL's revenue visibility, although the additional exposure to a single counterparty also increases customer concentration. It also underpins the resilience of the company's underlying operational frameworks. The additional time-charter agreements add approximately $750 million to SFL's fixed-rate charter backlog. It also pushes SFL's overall backlog figure to roughly $4.6 billion.
SFL's recent second quarter print also indicates management's focus on expanding its pipeline through long-term carrier and container charters. The quarter numbers relied heavily on two tankers benefiting from historic spot market trends. Topline went up from $174.5 million in Q1 to $201 million, while the adjusted EBITDA clocked in at $130 million. The company delivered $34 million in net income, translating into $0.25 earnings per share. Following an impressive quarter, the board announced a $0.22 per share dividend, marking SFL's 90th consecutive quarterly payout.
Counterparty Concentration and Market Cyclicality Risks
Despite its strengthening ties with well-reputed names such as Hapag-Lloyd, SFL carries a significant amount of counterparty concentration risk. The additional backlog increases SFL's exposure to Hapag-Lloyd, meaning a material deterioration in the carrier's creditworthiness or ability to honor its charter obligations could weaken SFL's cash-flow visibility.
Cyclicality within the container markets is also a major risk consideration, despite the current favorable landscape. Historically, the market has been characterized with volatility linked to variability in freight rates, vessel oversupply, and global trade volume fluctuations. Any downside scenario could adversely expose SFL to such cyclicality. Finally, it is important to highlight that although the fixed-rate exposure offers long-term earnings certainty, it may restrict the company from capitalizing on potential rate hikes further down the line.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.