Saving more may be a little easier than you think. Sign up for CNN’s Savings Challenge to find out how
CNN is offering a weekly newsletter with savings tips, expert answers to your questions and challenges to help you get your savings on track.
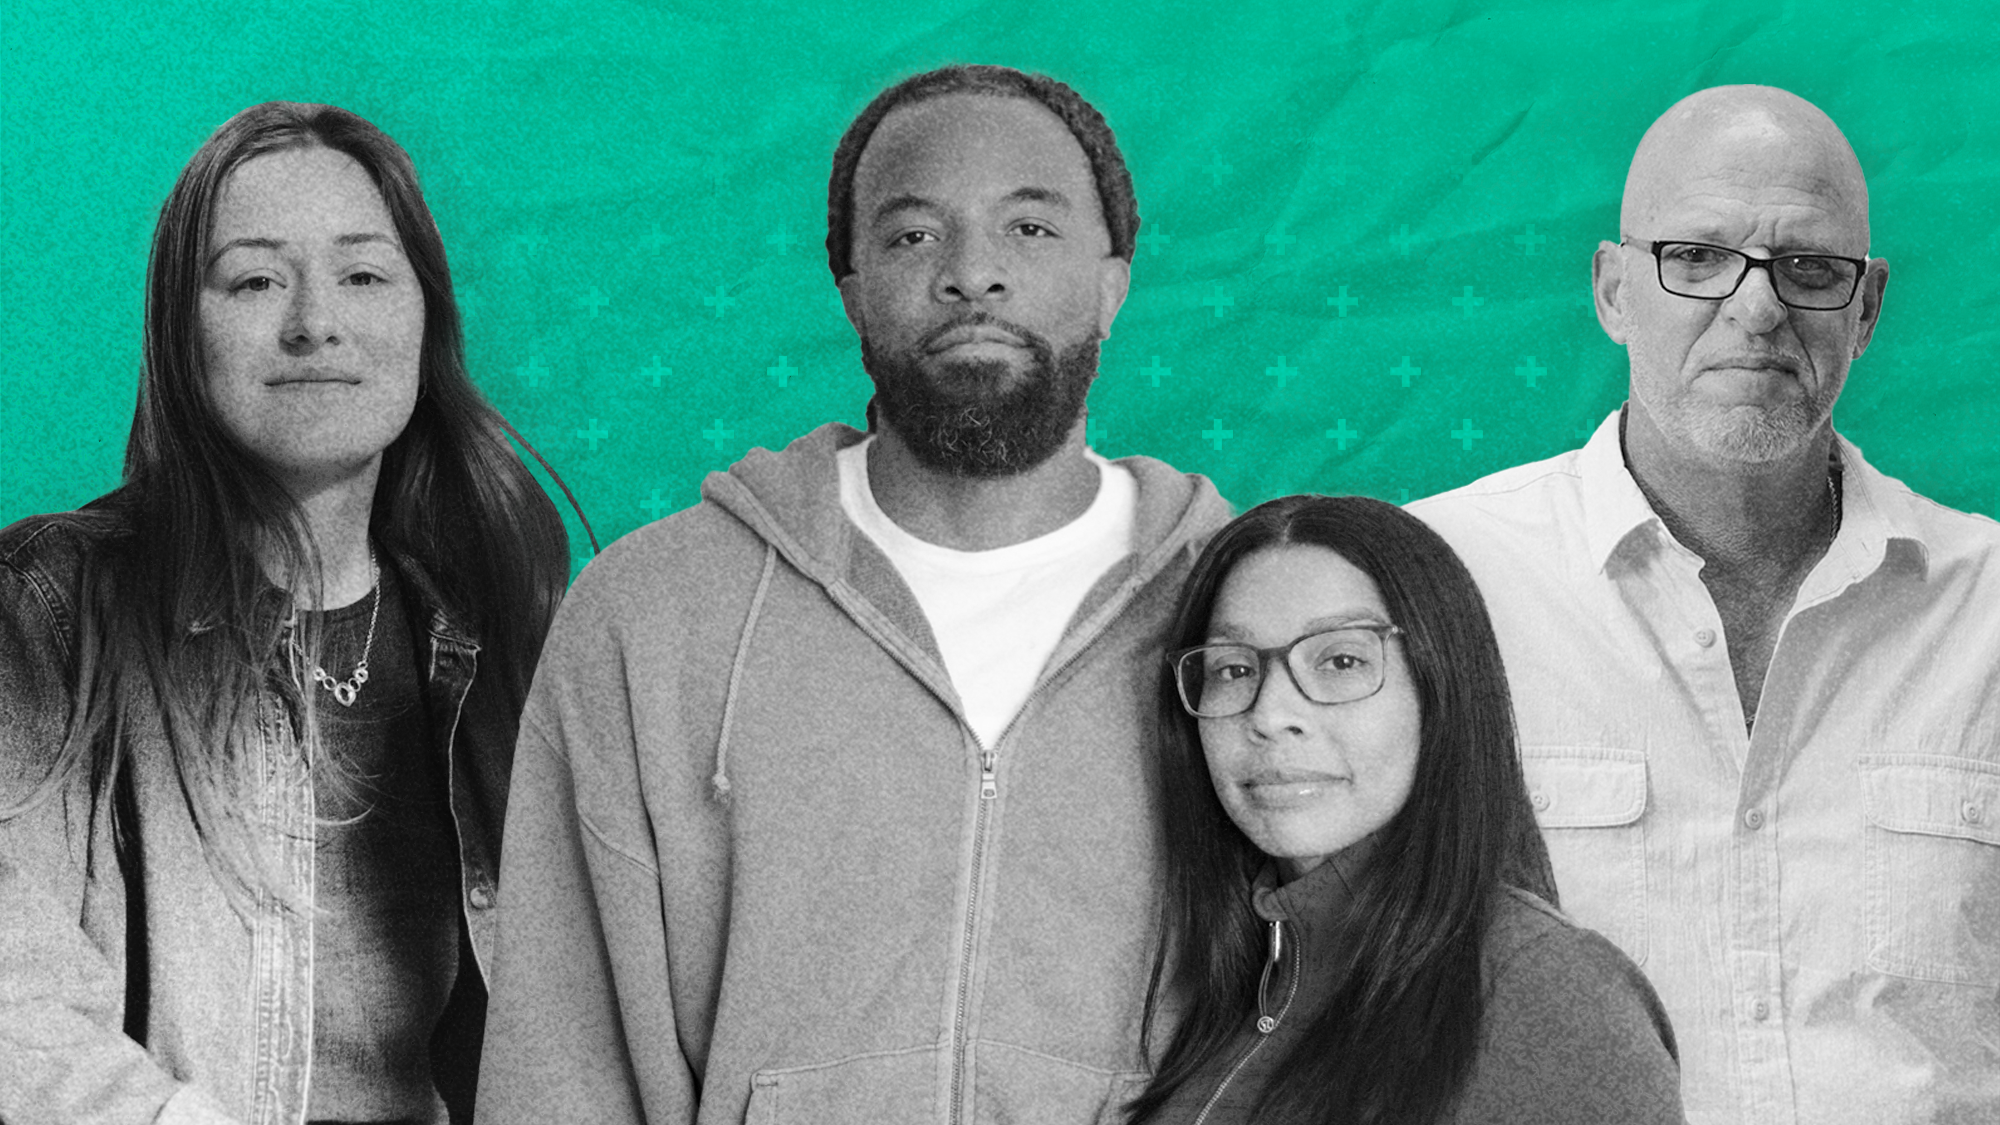
Like many people, you’d probably love to save more to do … well, everything. But life can be busy and expensive – increasingly so. And your list of financial obligations is already long. Still, taking just a little time to focus on where you’re at financially today versus where you’d like to be can help you find new ways to boost your savings – or at least get to a place where that can soon be possible. On October 2, CNN is launching a nine-week Savings Challenge. You’ll get a free newsletter every Friday that offers you a new challenge for the next week to help you build better savings and spending habits in ways that work for your life. These challenges will be part fact-finding mission and part treasure hunt. But that’s not all. We selected a handful of people to work one-on-one with a financial expert on their savings pain points. You’ll get updates on their progress and setbacks in each newsletter. And you’ll have a chance to submit your own savings questions and quandaries to certified financial planner Douglas Boneparth, who will offer advice in an Ask the Expert section. (You can sign up for the newsletter here.) CNN Savings Challenge Participants Mariza and Geffrey Gordon Ages: 40 (Mariza) and 39 (Geffrey) Income: $145,000 Savings goal: Build an emergency fund and stop living paycheck-to-paycheck Married couple Mariza and Geffrey Gordon recently relocated from Houston to their hometown of Milwaukee, Wisconsin. Mariza has two young adult sons from a prior marriage, one of whom still lives with the couple while the other is in college. Geffrey works as a business partner for schools at a leadership development company. Mariza was working as a plan consultant for a financial services company when the couple applied for the CNN Savings Challenge. But soon after, she learned she would be laid off and would get only two months’ severance. Other than directing a few hundred dollars toward their retirement savings every month, the couple said credit card debt, college tuition payments and inflation have made saving difficult. Combined, they said, they are making nearly $1,400 in minimum monthly payments just on their credit card debt. They also have more than $200,000 combined in student loans; at the moment, Geffrey said, their monthly payments are less than $75 a month. Jeff Kizer Age: 57 Income: $113,000 Savings goal: Eke out a little more in savings for retirement Jeff Kizer is a middle school algebra and geometry teacher at a private school in California. He also works as an independent tennis coach. He has one child from a prior marriage. Having lost a big chunk of his retirement savings in a divorce in 2019, Jeff said he has started saving about 25% of his income, thanks to advice he received when he first started at his school. He gets a 5% employer match on his 401(k) contributions from the school and a 3% match in a plan provided by the tennis facility where he coaches. Jeff also carries debt. He is paying off roughly $50,000 in federal student loans, which he took out for his master’s in education. He also is paying down a $33,000 personal loan, which he took out when he consolidated his credit card debt. Jeff lives with his wife in a home she owns. He pays her rent and they share living expenses. The couple generally keep their money separate, and his wife is not participating in this challenge. Abbey Graf Age: 28 Income: $74,000 Savings goal: Figure out if she is on track to buy a house and eventually retire comfortably Abbey Graf has saved a sizable sum for her age and income. Single with no kids, Abbey is a contractor who works full time as a food stamp policy analyst for the state of Wisconsin. But because she is a contractor, she doesn’t have access to an employer-based retirement plan – or any employer matches – nor does she qualify for the state pension system. To compensate, Abbey has been socking away 25% of her after-tax income across a Roth IRA, a brokerage account and, just this year, a health savings account. Combined, she’s now putting away a little more than $1,200 a month in automated savings, she said. Abbey also has built up a substantial emergency fund, which could cover her living expenses for more than a year if necessary. Her frugality stems partly from knowing things happen in life that she has no control over. “What if I can’t work to 65? What if I can’t save for retirement for five years?” she said. “Everything that is going on… it just feels like things are uncertain.”
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.