Nobody Wants to Inherit a Villages Home. Here’s What It Costs the Kids When They Do
Leaving a Villages home to your kids sounds like a gift, but the legal restrictions, tax resets, and monthly carrying costs can turn an inheritance into a fi...
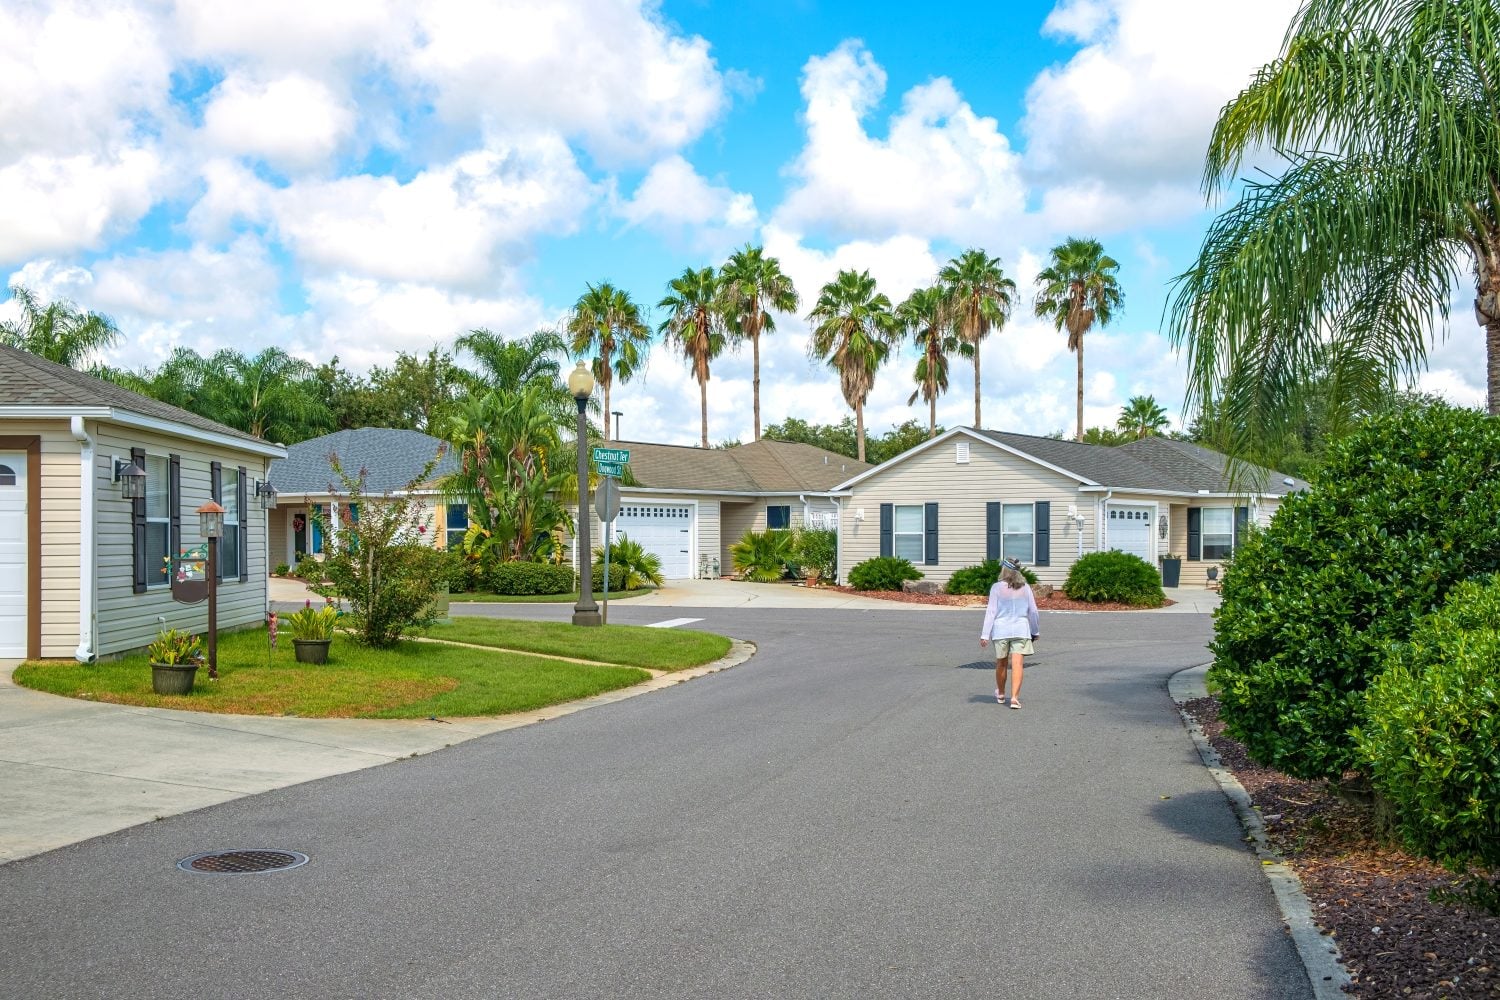
Florida's Save Our Homes cap removal at death can double or triple a Villages home's property tax bill for non-spouse heirs overnight.
Federal age-restriction law bars any heir under 55 from living in the inherited home, forcing an immediate choice between selling or renting to age-qualified tenants.
Empty-house costs such as reset taxes, amenity fees, bond assessments, and vacant-dwelling insurance accrue for six to twelve months while Florida probate clears before any sale can close.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Most conversations about a home in The Villages end at the closing table, when the retiree buys in and starts pricing golf carts for the right reasons, as the lifestyle is very appealing. However, the question that rarely gets asked out loud is what happens when you are gone, and the house passes to your kids in Denver, Boston, or Seattle, none of whom can use it. Current or future owners need to consider this clearly, with clear eyes on what your children will actually face and what you can do about it while you still can.
The Villages qualifies as age-restricted housing under the federal Housing for Older Persons Act. At least one occupant of each home must be 55 or older, at least 80% of homes must house someone 55-plus, and no one under 19 may live there permanently. If your adult child is under 55, they legally cannot occupy the house they just inherited. Their choices collapse to two: sell it, or rent it under the community's rules. Rentals require a minimum 30-day lease, tenants must meet the age requirement, and the district requires rental registration. The asset they received is one they are structurally barred from using.
The 4% Rule is Broken, Built On A World That No Longer Exists
Every retiree knows about the 4% rule, but it frames retirement as a slow liquidation and still causes retirees with seven-figure accounts to agonize over a dinner out.
There's a different way to run the math that makes more sense today. Build an income floor — dividends, interest, and Social Security that cover your essential bills every month — and you never have to sell shares into a down market just to pay them.
Our free reader guide, The 4% Rule Is Broken , walks through it in about 15 minutes. Access the report here.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.