Bessent says inflation and bond yields will drop when the Iran war ends. Others aren't so sure.
Treasury Secretary Scott Bessent says inflation and bond yields will come back down once the conflict in Iran ends. Is he right?
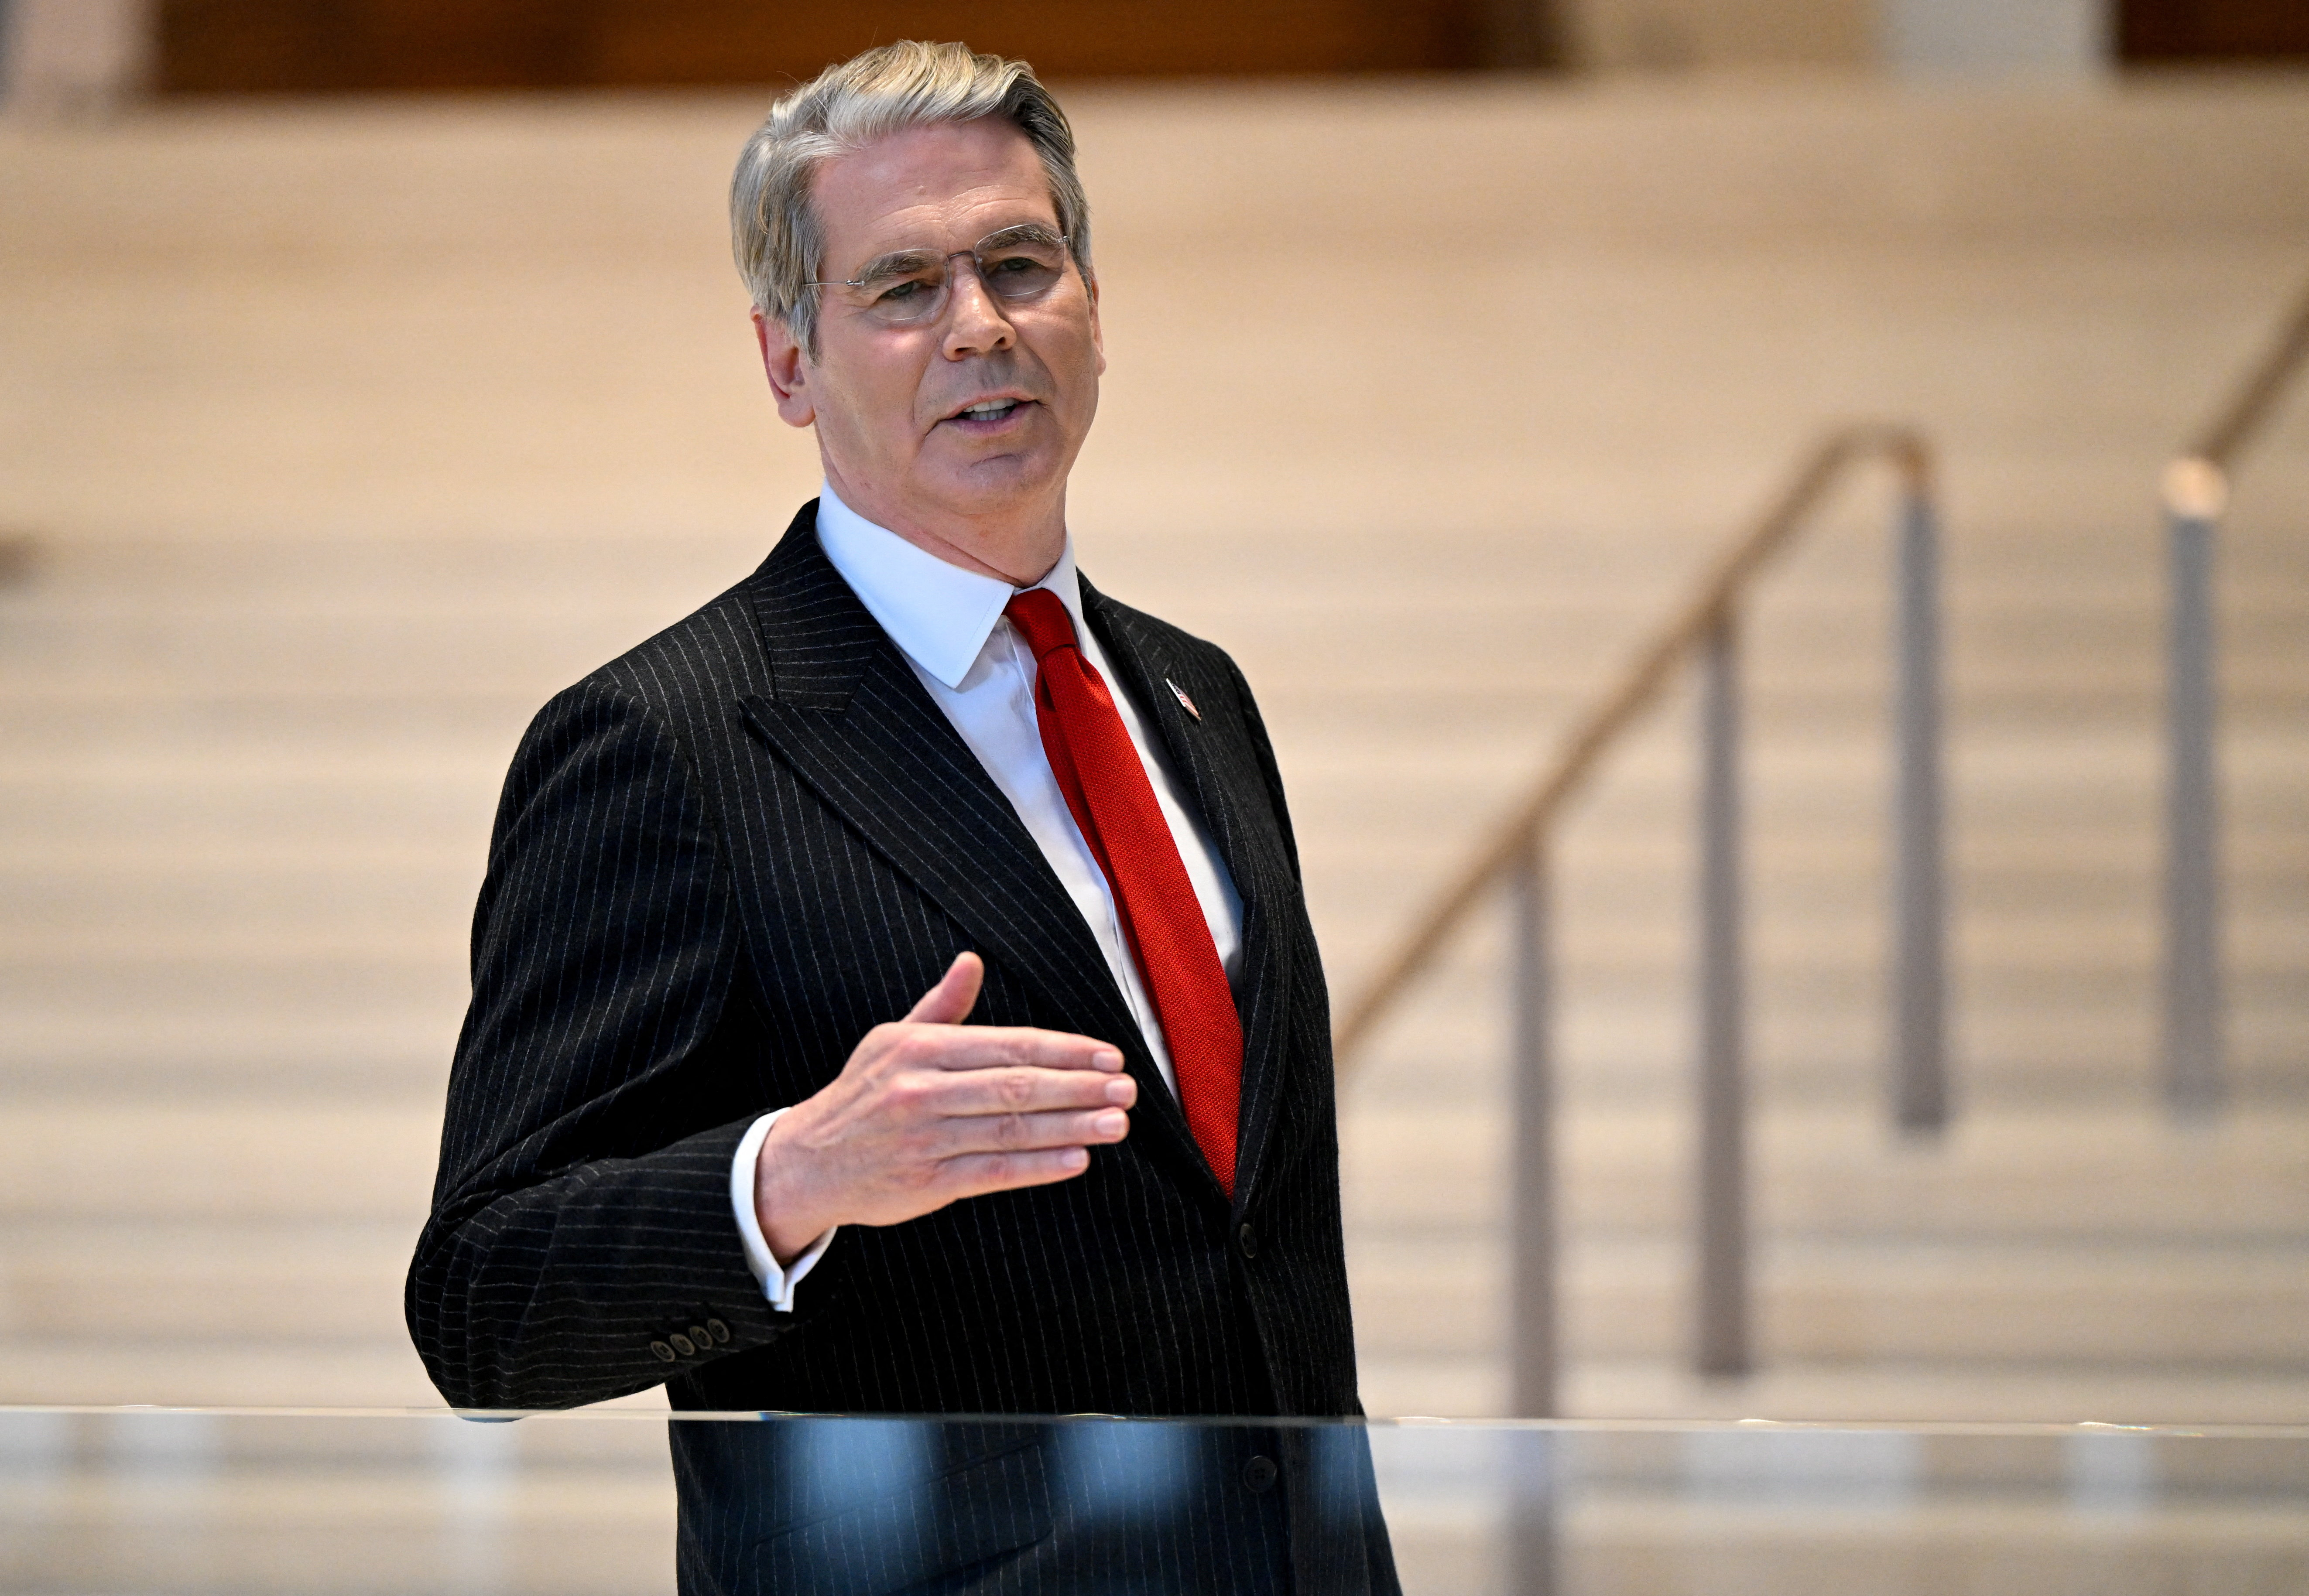
Treasury Secretary Scott Bessent says the economy is "accelerating" and inflation, along with bond yields, will come back down once the conflict in Iran ends.
"Right now, we have this energy shock that's generated by the Iran conflict, and headline inflation is about 3.5%. But my message is underlying inflation — core inflation — is down to about 2.3%," Bessent said at the Pennsylvania Chamber of Commerce on Monday night.
He asserted that median wage growth is in line with headline inflation, and that "we will get to the other side of this Iran conflict. Energy will come back down, and the wage growth will continue."
He said 1 million private sector jobs have been created this year, while government jobs have been trimmed by 300,000.
"Real wage growth comes from private sector jobs, and I think we're just starting to see the acceleration here," he said.
But not everyone sees the wage picture the same.
Gregory Daco, chief economist for EY, notes that average hourly earnings rose at an annualized pace of 3% in September , marking the slowest pace of the post-pandemic cycle. He said he expects inflation in September, as measured by the Consumer Price Index, to clock in at 3.6%, and as a result, he anticipates that wages adjusted for inflation will likely fall 0.6% year over year, marking a sixth consecutive month of contraction.
"While strong wealth effects from stock market gains continue to support solid aggregate consumer spending, the growing income squeeze affecting households is likely to cap spending growth heading into 2027," Daco said.
Joe Brusuelas, chief economist for RSM, agrees that the economy accelerated into the third quarter, but he asserts that inflation is not easing, pressuring wages and purchasing power.
Brusuelas maintains that the CPI report due out next week will show that wage growth adjusted for inflation has been flat to negative since the start of the Iran war.
"It's far more likely that declining real wages begin to act as a mild drag on growth heading into the final quarter of 2026 and early 2027," he said.
Higher bonds: strong economy or oil prices?
Bessent also addressed the spike in long-term Treasury yields, saying he believes the run-up is a function of headline inflation and higher energy prices stemming from the war. Once the conflict ends, he said, longer-term bond yields will come down to levels seen in mid-February before the war.
"I don't know if this conflict's going to end next week, next month, in two months, but I believe on the other side of this, energy prices will be much lower and interest rates, mortgage rates will come back down," he said.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.