In 2020, five rainstorms damaged a Georgia solar project; insurer later tried to apply a $2.5 million deductible after paying $600,000
Five heavy rainstorms damaged a solar power project in Georgia between December 2019 and April 2020, leading to an insurance dispute over how the losses
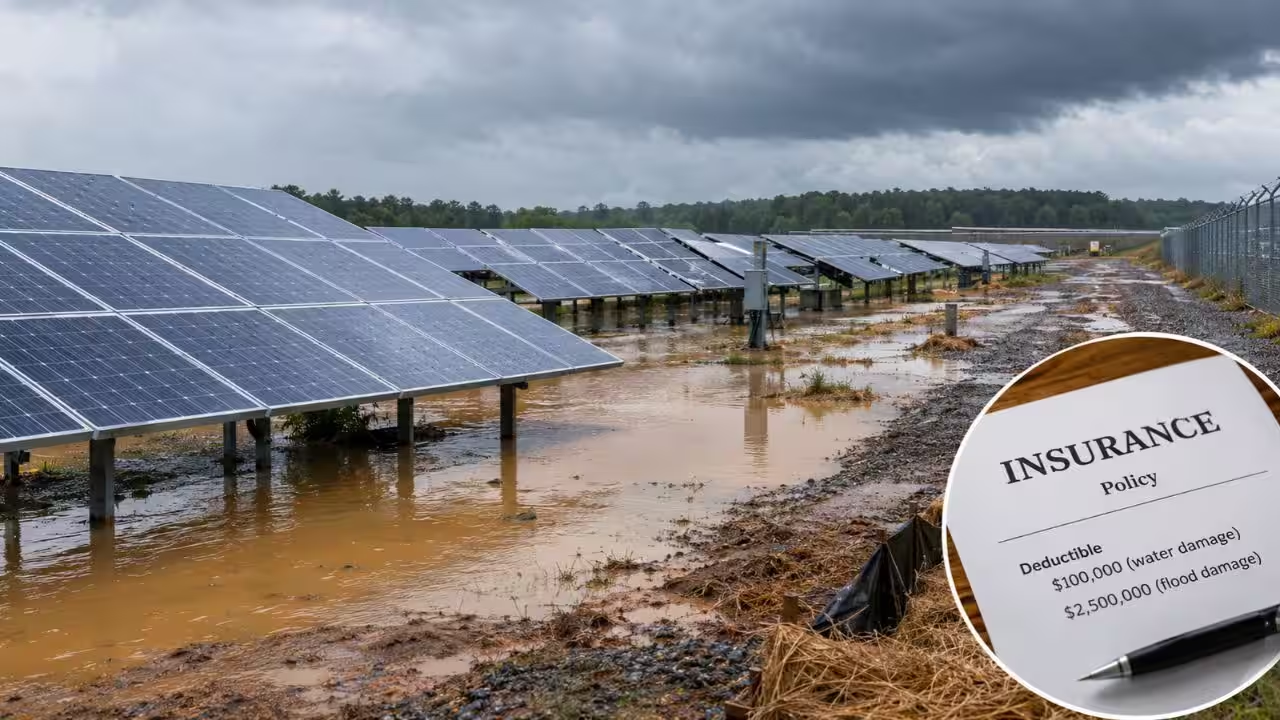
Five heavy rainstorms damaged a solar power project in Georgia between December 2019 and April 2020, leading to an insurance dispute over how the losses should be classified. Zurich American Insurance Company initially treated the damage as water-related and made payments totalling $600,000 to First Solar Electric LLC. The insurer later argued that the incidents should be classified as flooding, which carried a much higher deductible of $2.5 million per event. In an October 2026 ruling, a federal appeals court examined whether the insurer could change its position after making the earlier payments.Why did the Georgia solar project face a $2.5 million deductibleThe dispute concerned a large solar power plant that First Solar was constructing in central Georgia. According to the US Court of Appeals for the Eleventh Circuit in its October 2026 opinion, the project covered 1,038 acres and was insured under a master builders risk policy purchased from Zurich American Insurance Company.The policy covered physical damage to the insured property during the construction period. Its coverage ran from 24 August 2017 to 24 August 2020, placing all five rain-related incidents within the insured period.The storms occurred on or around 13 December 2019, 5 February 2020, 13 February 2020, 3 March 2020 and 18 April 2020. As the court explained in its judgment, rainwater accumulated on the ground and spread across the site, damaging solar arrays, access roads, security fences and other construction work, including electrical and structural components.InsuranceJournal reported that the facility was a 200-megawatt solar plant. The damage triggered claims under a policy that treated water damage and flood damage differently, making the classification of each incident central to the dispute.The policy made a distinction between water damage and floodingThe insurance contract set two substantially different deductibles, depending on how the damage was classified. A deductible is the amount that must be accounted for by the insured before the insurer pays for a covered loss.Under the policy, water damage carried a deductible of $100,000 for each event. Flood damage, however, attracted a deductible of $2.5 million per event. The difference meant that the classification could determine whether First Solar received an insurance payment.The Eleventh Circuit's opinion explained that the policy's definition of flooding included the unusual and rapid accumulation or runoff of surface water that temporarily inundated normally dry land. Water damage covered damage caused by water from any source, except damage falling under the policy's flood definition or resulting from a named storm.These provisions became important when Zurich reconsidered its initial assessment. Although the insurer eventually concluded that the incidents qualified as flooding, the court had to determine whether the company could apply the higher deductible after already making payments under its earlier decision.How did Zurich change its position after paying $600,000Zurich assigned adjuster Scott Klaben to investigate First Solar's claims. According to the court's account, Klaben inspected the project in February 2020 and initially recorded the losses as water damage.The insurer subsequently issued three advance payments of $200,000 each for the first three rain events. Together, these payments amounted to $600,000.The court noted that Zurich had not reserved its right to change its coverage decision before making those payments. In other words, the company did not state that it might later reconsider the classification and apply a different deductible.Zurich subsequently reversed its position, treating the losses as flood damage instead of water damage. Because the deductible for flooding was $2.5 million per event, the insurer concluded that the claimed losses did not exceed the applicable deductible and that no further payment was due. It then closed the claim.Insurance Journal reported that this change led to litigation, with First Solar challenging the insurer's attempt to apply the higher deductible after the initial payments.The appeals court examined whether the insurer could reverse its decisionFirst Solar brought the dispute before the US District Court for the Middle District of Georgia. The district court ruled that the flood deductible applied under the policy but that Zurich had waived its right to impose it on the rain-related claims. It also rejected the insurer's argument concerning the timing of the lawsuit.The case proceeded to a trial focused on damages, and a jury found in favour of First Solar. The district court subsequently awarded the company $12.2 million, including interest calculated before the judgment.Both parties appealed aspects of the decision.In its 22 October 2026 opinion, the Eleventh Circuit considered whether Georgia law allowed Zurich to apply the higher deductible after making unconditional payments based on its earlier coverage determination.The court concluded that Zurich had waived its right to apply the flood deductible to the first three incidents. Its reasoning focused on the insurer's initial decision and its failure to reserve the right to change that decision before issuing the payments.As reported by Insurance Journal, the appeals court found that Zurich could not simply reverse its earlier position and impose the higher deductible on those three claims.The ruling leaves two rain events open for further proceedingsThe appeals court did not resolve every aspect of the dispute in First Solar's favour. Its judgment distinguished between the first three rain events and the two later incidents, which occurred on 3 March and 18 April 2020.For the first three events, the court upheld the conclusion that Zurich had waived its right to apply the flood deductible. However, it found that a genuine dispute remained over whether the insurer had also waived that right for the final two incidents.The Eleventh Circuit therefore vacated the judgment concerning the March and April events and sent that part of the case back to the district court for further proceedings. The court also upheld the denial of Zurich's request to strike one of First Solar's witnesses as a sanction.Zurich cannot apply the higher flood deductible to the first three rain events after waiving that right through its earlier actions, while the claims involving the final two incidents require further consideration by the lower court.You use AI every day. Now get your AI Quotient. Take the AIQ test.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.