Canadian billionaire Kevin O' Leary: Follow this rule, and you will be a millionaire when you retire
Tech News News: Kevin O’Leary has suggested a simple rule for Americans looking to build a seven-figure retirement portfolio. The Shark Tank US judge has recommended .
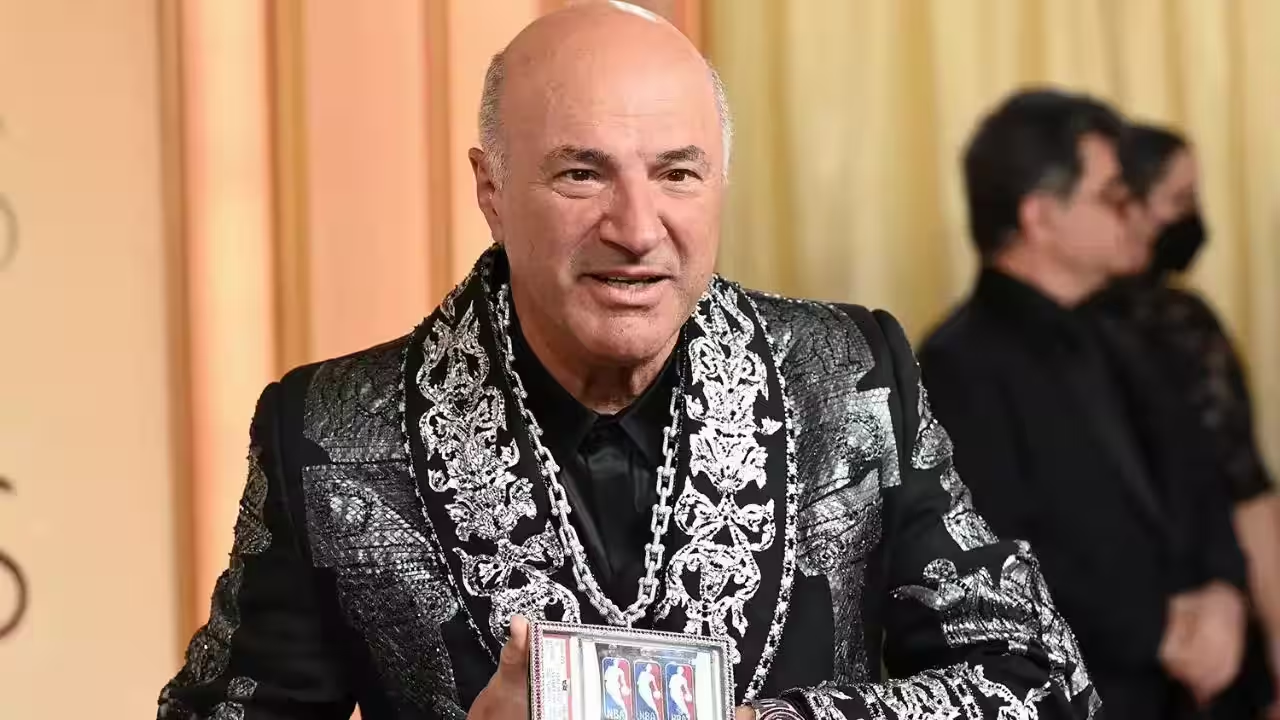
Kevin O’Leary has suggested a simple rule for Americans looking to build a seven-figure retirement portfolio. The Shark Tank US judge has recommended saving and investing 15% of every paycheque and letting the money compound over time. For someone earning $68,000 a year, the investor says consistently following that approach could result in a millionaire-sized retirement portfolio by age 65. The Canadian investor and entrepreneur recently shared the advice in an Instagram post, telling people to put money into the market rather than spend it on things they do not need. His calculation assumes decades of consistent investing and relies on long-term stock market growth.“What piece of advice do I give my kids over and over and over again about money? Don't spend it. Save it, invest it, let it compound. That's the gift the market gives you. Take 15% of all your paycheques, all your side hustle, any cash Granny gives you, put it in the market, and just let it compound. If you make $68,000 a year, the average salary, and you do this your entire life, just 15% of your paycheque- you'll end up a millionaire by retirement in '65. Best piece of advice I can give anybody. Don't buy stuff you don't need; invest it instead. Cheers,” O’Leary said in the post.How Kevin O’Leary’s 15% savings rule worksBy his example of an income of $68,000, that would mean a 15 per cent contribution of roughly $10,200 a year, or $850 a month. If you invested that amount consistently for 40 years, from age 25 to 65, your portfolio could grow substantially with compound returns.The strategy is straightforward on paper, but putting aside 15% of income can be difficult for households already dealing with rent, food, student loans and other living costs.The calculation depends heavily on investment returns and how long the money stays invested. Assuming an average annual return of about 10%, broadly in line with the S&P 500's historical long-term average, investing $850 every month for 40 years would produce approximately $5.3 million.At a lower assumed average return of 7 per cent, that same monthly contribution would have accumulated to about $2.2 million over four decades. In either case, the investor would have more than $1 million at retirement. Remember that actual investment returns can vary from year to year and are not guaranteed.So O’Leary’s estimate is an illustration of long-term compounding rather than a guaranteed outcome. It also assumes the worker can contribute uninterrupted over a 40-year career.Why saving 15% can be difficult for average workersThe challenge is less about the arithmetic than whether an average household can consistently set aside that much money. Workers earning between $50,000 and $79,999 are among those most likely to report falling behind on retirement savings, with 55% saying they feel behind.According to the Bureau of Labor Statistics, the personal savings rate was 4.4% of disposable income in mid-2025, a Fortune report noted. For a $68,000 earner, that would be about $3,000 a year, a far cry from the $10,200 annual investment suggested by O’Leary’s 15% rule.Vanguard data also show that the median total contribution rate among 401(k) participants, including employee and employer contributions, is about 11.5%. That figure applies mainly to workers with access to a 401(k), so it does not represent the entire workforce.What a $68,000 salary looks like after basic expensesAn American household making $68,000 before taxes will take home about $52,000 to $54,000 after federal and state taxes. This will leave about $3,600 a month for other expenses.Average US rent is about $1,740 a month, according to RentCafe. That would leave around $1,860 before other household costs. Groceries can add as much as $400 a month for a single person based on Bureau of Labour Statistics data, reducing the amount further.The remaining amount could drop to around $726 with student loan payments averaging about $434 a month and utilities at about $300. That would mean that saving $850 a month would be more than what you would have left after all of the expenses above.Even if the calculation is based on 15% of take-home income rather than gross pay, the target is still substantial. Nearly $52,000 in annual take-home income is about $650 a month at 15 per cent, which might still leave only about $150 in discretionary income under the expense assumptions.How Warren Buffett’s advice comparesO’Leary agrees with Buffett’s long-term, low-cost approach to investing. Buffett has said that on the whole, average investors are better off with low-cost S&P 500 index funds than paying high fees to professional managers.“Put 10% of the cash in short-term government bonds and 90% in a very low-cost S&P 500 index fund. (I suggest Vanguard’s),” Buffett wrote in a 2013 shareholders’ letter. “I believe the trust’s long-term results from this policy.”Get the latest technology news and updates. Download the TOI App.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.