AI Memory Chip Selloff Looks Overblown: 2 Stocks to Buy on the Dip
Micron and Sandisk emerge as attractive buy-the-dip opportunities despite the memory stock sell-off, backed by strong AI demand and long-term growth prospect...
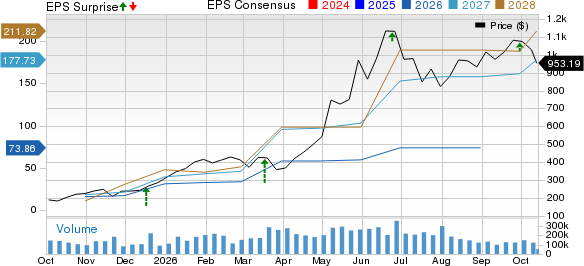
Memory stocks are facing fresh selling pressure since Monday as investors question the sustainability of artificial intelligence (AI)-related spending and worry about rising competition. The latest trigger came from China's ChangXin Memory Technologies, which reported progress over the weekend on a new DRAM architecture that it claims could boost memory density by 30-50%, allowing more data to be stored in the same physical space.
The market reaction has been sharp. Per CNBC, SK Hynix and Samsung Electronics dropped more than 10% and 7%, respectively, yesterday in Seoul. Both touched their lowest levels since August.
In the United States, Micron Technology MU, Sandisk Corporation SNDK, Seagate Technology Holdings STX and Western Digital Corporation WDC have also come under pressure. Over the past two trading sessions, shares of Micron, Sandisk, Seagate and Western Digital fell 4.4%, 6.2%, 4.5% and 4.1%, respectively, reflecting growing nervousness across the memory sector. Investors were already worried about how AI spending is being financed, so the CXMT news landed on a fragile market.
However, the sell-off may be getting ahead of itself. Although CXMT's technological progress could intensify competition over time, the company still needs to prove that it can manufacture its chips at scale. Legacy memory makers still hold a technological lead over CXMT.
For investors, this pullback could present an opportunity rather than a reason to panic. Micron and Sandisk are worth buying now on the recent dip, as both are set to benefit from continued demand for memory and storage driven by AI infrastructure.
Let's assess why these two stocks still offer attractive opportunities despite the recent volatility.
Micron closed fiscal 2026 on a strong note, with record revenues, high margins and strong cash generation. The outlook is even more striking. The company expects fiscal first-quarter 2027 revenues of $61.5 billion (plus or minus $1.5 billion) and adjusted earnings of $38.15 per share (plus or minus $1), implying roughly 351% revenue growth and 698% earnings growth from a year ago.
HBM revenues grew faster than Micron's total revenues in the fiscal fourth quarter, and the company has already contracted most of its 2027 HBM supply at significantly higher prices. Its HBM4 ramp is progressing, and it is working with NVIDIA on a custom HBM4E solution. NAND is a second engine, with data center SSD revenues approaching $10 billion in the fiscal fourth quarter, more than 10 times the year-earlier level, as uses like KV-cache offload widen demand for fast storage. Further out, autonomous vehicles and humanoid robots should need far more memory and storage than today's devices.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.