IonQ (IONQ) Just Gave Investors Something To Think About
IonQ (IONQ) just inked a multi-year alliance with South Korea based SDT Inc., focused on delivering its Superion 256 quantum computer and SiV memory, and on...
IonQ (IONQ) just inked a multi-year alliance with South Korea based SDT Inc., focused on delivering its Superion 256 quantum computer and SiV memory, and on building a dedicated quantum manufacturing hub in Gumi.
Set against a 1-day share price return of 0.57% and a 7-day share price gain of 9.96%, IonQ's recent SDT deal and Superion 256 launch come after a tougher stretch where the 90-day share price return fell 23.99% and the 1-year total shareholder return declined 45.78%, even though the 3-year total shareholder return remains very large at about 3x, signalling strong long term momentum but a more cautious recent reset around execution and risk.
Scan beyond IonQ and see how other quantum and AI infrastructure plays stack up in our hand picked list of 25 quantum computing stocks .
IonQ now trades at a steep 65% discount to the average analyst target even after the SDT news bounce. Is that caution around losses and execution discipline, or has sentiment swung too far?
IonQ's most followed valuation story pegs fair value around $48 per share, which sits above the last close at $40.74 and presents the stock as discounted relative to that narrative anchor.
IonQ's biggest advantage is still the same one it had before, but it is more visible now, it is the best-funded, broadest, and most commercially scaled public quantum company. At the end of 2025, IonQ had $3.3 billion in cash, cash equivalents, and investments, which remains an enormous strategic asset in a capital-intensive sector.
According to HedgeY, this combination of a large cash reserve, a broad quantum platform, and commercial traction supports a fair value of $48 per share, which implies IonQ trades at roughly a 15% discount to that narrative estimate today. The same narrative highlights valuation, execution risk, and continued losses as important counterweights, so that $48 is presented as a balanced view rather than a one-sided bullish call.
Still, IonQ's heavy losses of US$1.36b on just US$246.47m of revenue, along with the recent 1 year share price decline of 45.78%, could quickly pressure that 15% undervalued story.
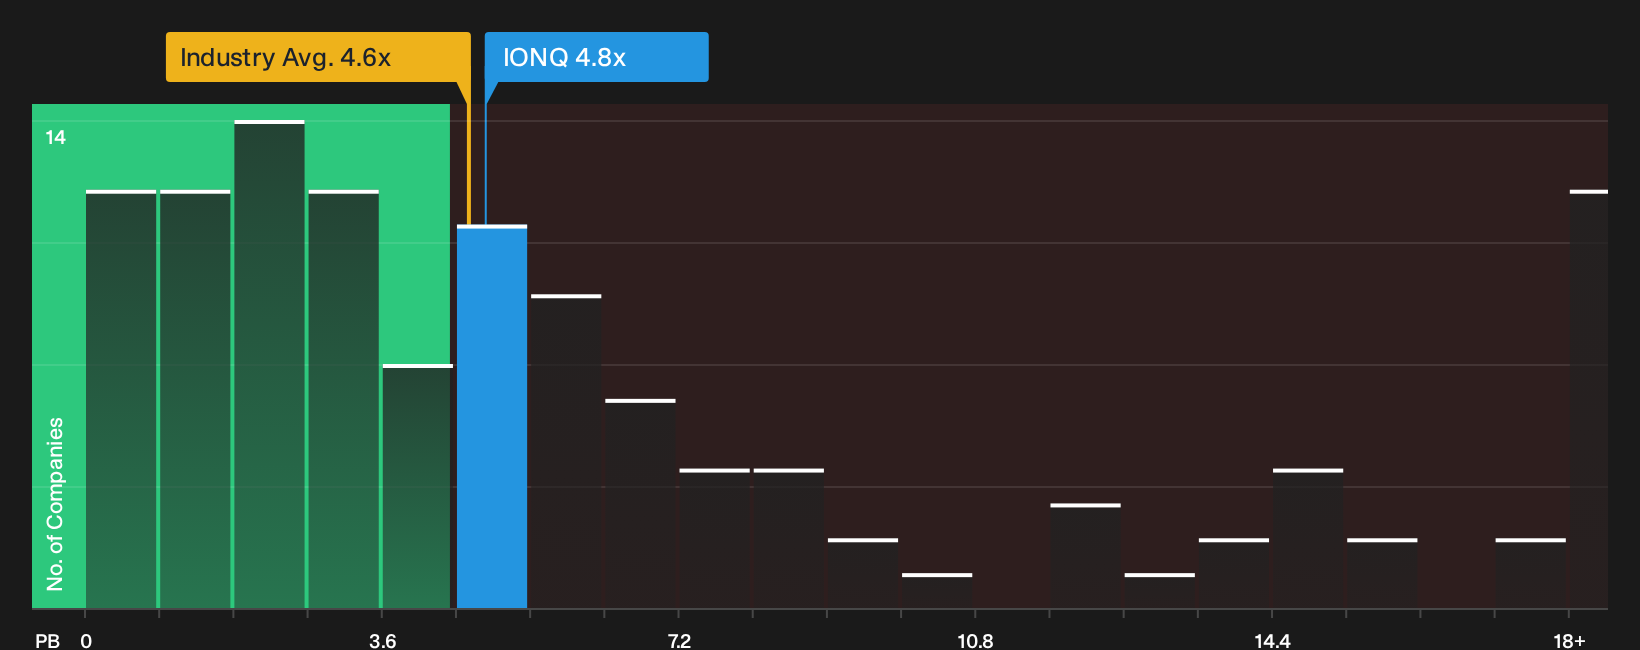
IonQ can appear inexpensive from one perspective and costly from another. On a price-to-book ratio of 4.9x, the stock trades slightly above the US Semiconductor industry at 4.6x but well below its peer group at 12x. That combination suggests both downside risk and upside potential. Which crowd is right?
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.