CMBS Special Servicing Hits Highest Rate Since 2013
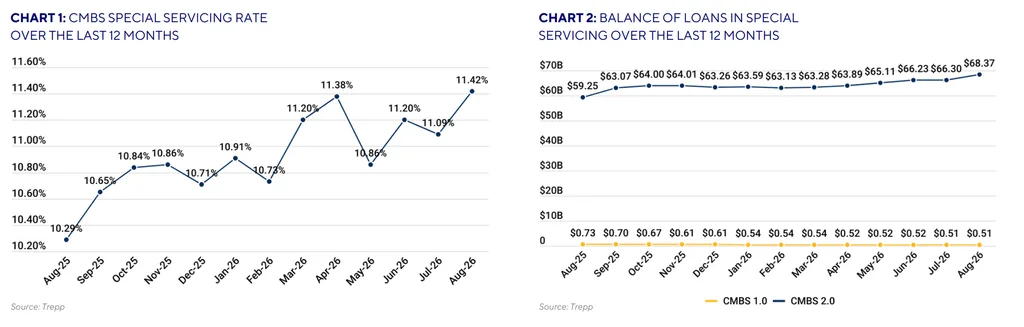
The CMBS special servicing rate climbed to 11.42% in August as large office, mixed-use, retail, and hotel maturities drove transfers.
This story was originally published on CRE Daily . Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry analysis delivered straight to their inbox with the free CRE Daily newsletter .
The overall CMBS special servicing rate rose 33 basis points in August to 11.42%, its highest level since February 2013.
New transfers totaled $3.16B across 32 whole loans, with large office and mixed-use maturities driving most of the increase.
Only about $500.7M across 14 loans exited special servicing, leaving upcoming office and mixed-use maturities as the key near-term pressure point.
Trepp's August report shows that large maturity defaults pushed the CMBS special servicing rate higher after July's decline. The overall rate increased 33 basis points to 11.42%, the highest since February 2013. New transfers reached $3.16B across 32 whole loans, nearly twice July's total. Loans that cured, returned to master servicing, or paid off totaled only about $500.7M across 14 whole loans.
The biggest transfer was the $1.10B Los Angeles Office/Studio Portfolio, which Trepp had identified as August's largest hard maturity. The floating-rate loan is backed by a Hollywood studio-and-office portfolio and represents the full BXHPP 2021-FILM single-asset deal. It transferred before its August 9 maturity after exhausting extension options.
The loan remained current at maturity and reported a 1.45x debt service coverage ratio on net cash flow. The borrower and special servicer agreed on a framework for a longer extension and executed a 30-day extension while documents were completed. Because Trepp classifies the collateral as mixed-use, the loan accounted for essentially the entire 154-basis-point jump in that category.
The second-largest transfer was the $377.6M Project James loan, secured by eight office buildings in greater Washington, DC. It moved to special servicing for an imminent balloon and maturity default. Unlike the Hollywood portfolio, the loan failed to pay off at maturity and carried a non-performing matured balloon status. Its latest DSCR was 1.30x.
Other large transfers included 111 Livingston Street and 60 Madison Avenue in New York, the Hyatt Regency New Orleans, Fresno Fashion Fair Mall, and Harlem USA. Trepp noted that several loans were still current when transferred. That pattern shows how August's rise was driven heavily by refinancing and maturity pressure rather than only missed monthly payments.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.