Micron (MU) Is Down 5.6% After Netlist Deal, Strong Earnings And Dividend Affirmation - What's Changed
In early October 2026, Micron Technology reported past-year results showing sharply higher sales and net income, affirmed a quarterly US$0.1500 per-share div...
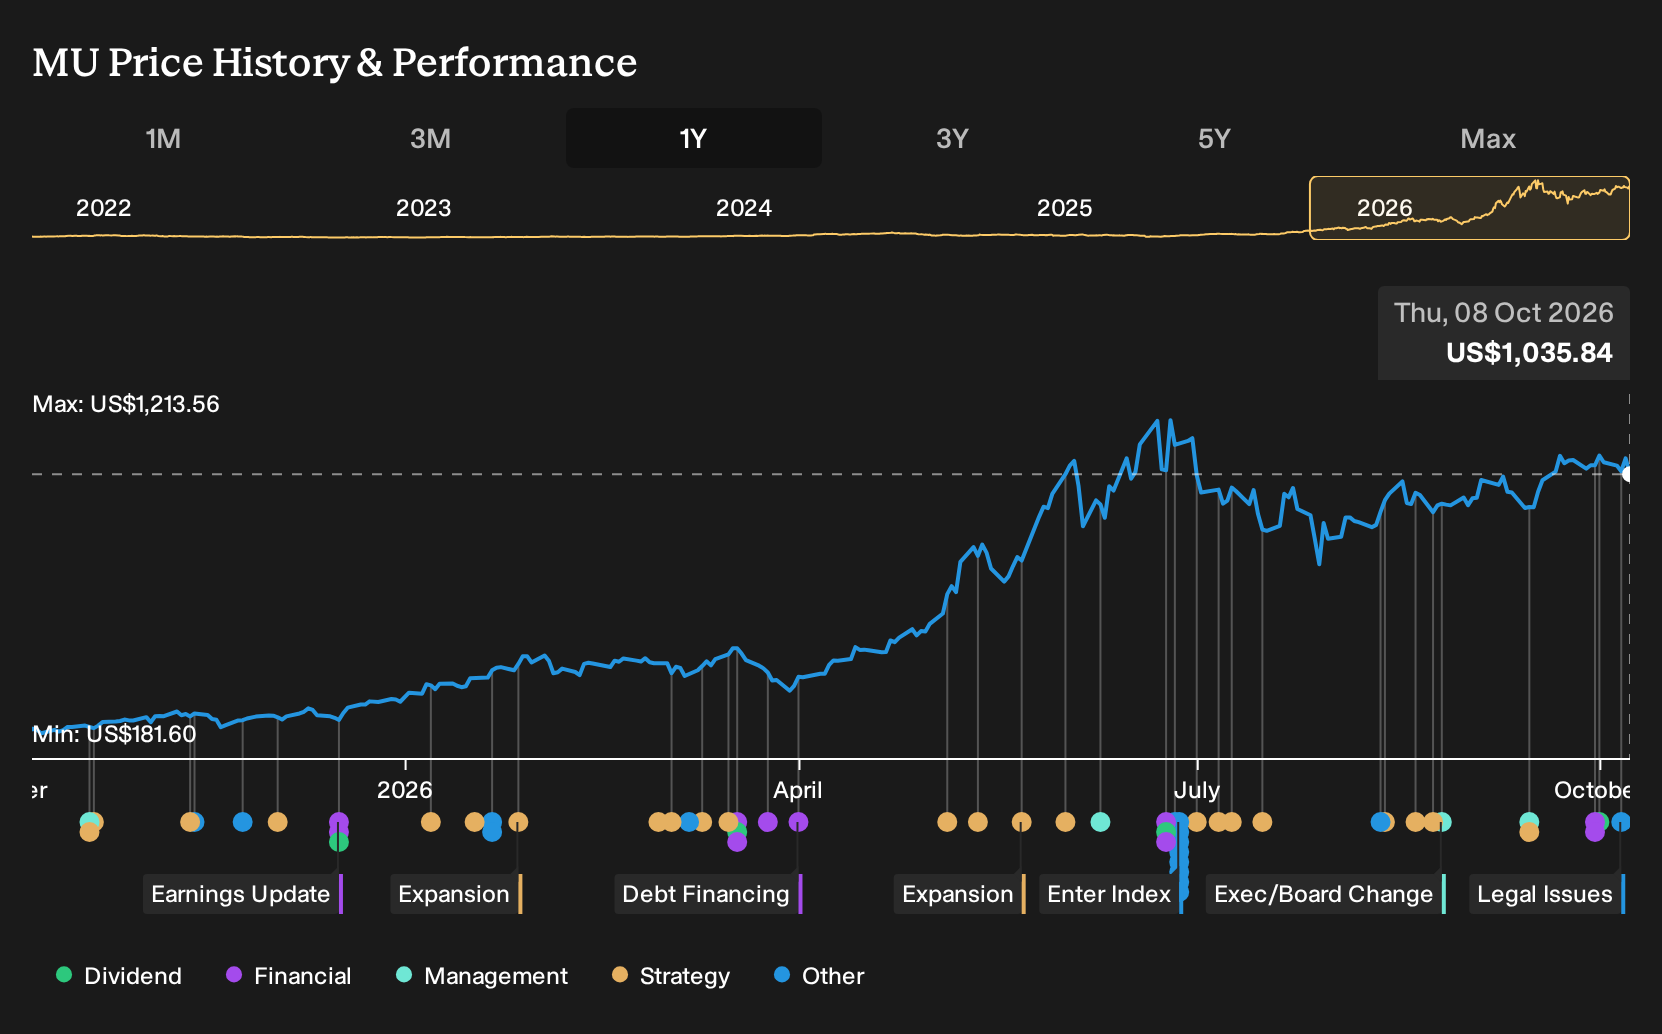
In early October 2026, Micron Technology reported past-year results showing sharply higher sales and net income, affirmed a quarterly US$0.1500 per-share dividend, and entered a five-year, US$600 million patent license and settlement agreement with Netlist that includes quarterly payments of US$30 million starting in the fourth quarter of 2026.
The Netlist settlement removes a major legal overhang just as Micron leans on AI-driven demand, with a long-term license covering key server DIMM and high-bandwidth memory patents that underpin its data center offering.
Next, we'll examine how resolving the Netlist dispute and securing critical memory IP could reshape Micron's investment narrative around AI-led growth.
AI is about to change healthcare. These 32 stocks are working on everything from early diagnostics to drug discovery . The best part - they are all under $10b in market cap - there's still time to get in early.
Micron Technology Investment Narrative Recap
To own Micron here, you need to believe AI data center demand can sustain high-margin growth long enough to justify massive factory spending, even as competition and eventual memory normalisation loom. The Netlist settlement meaningfully reduces legal risk around core server and HBM products, but near term the biggest swing factor is still AI-driven demand and pricing, while the key risk is that heavy capital outlays collide with any slowdown or oversupply in DRAM and NAND.
The most relevant recent announcement is Micron's blockbuster fiscal 2026 report, with US$133,188 million in revenue and US$84,969 million in net income, alongside stronger guidance for early fiscal 2027. That earnings power gives Micron more room to absorb the US$600 million Netlist payments while still funding elevated capex and potential buybacks, which ties directly into the bull case that AI-led memory demand can keep margins and free cash flow healthy even as spending climbs.
Yet beneath the optimism around AI and legal clarity, rising labor tensions and the risk of higher ongoing compensation in Taiwan are things investors should be aware of...
Micron Technology's narrative projects $297.7 billion revenue and $184.0 billion earnings by 2029. This requires 48.9% yearly revenue growth and a $133.5 billion earnings increase from $50.5 billion today.
Before this settlement, the most optimistic analysts were already assuming Micron could reach about US$391 billion in revenue and US$232 billion in earnings by 2029, so you should expect those blue sky views and the concerns about Taiwan labor unrest to evolve as the story develops.
Gathered from external sources. Rights to this text belong to whoever originally published it.