Should You Hold on to Cerebras Stock Despite Its 25% One-Month Dip?
CBRS stock plunges 25.3% in a month, but surging AI demand, a $25.4 billion backlog, and capacity expansion support growth despite margin pressures.
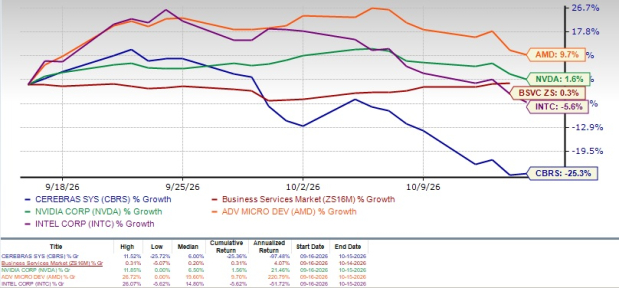
Cerebras CBRS shares have plunged 25.3% in the past month, underperforming the broader Zacks Business Services sector, which returned 0.3%. The company's shares have also underperformed its competitors, which include NVIDIA NVDA, Advanced Micro Devices AMD, and Intel INTC in the AI space. Shares of NVIDIA and Advanced Micro Devices gained 1.6% and 9.7%, respectively, while Intel lost 5.6% over the past month. The underperformance can be attributed to near-term margin pressure from higher costs associated with renting back systems to expand its cloud capacity. Data center availability constraints and deployment delays could limit revenue growth, while significant investments in manufacturing and infrastructure weigh on profitability. Heavy dependence on OpenAI poses customer concentration risks.
However, Cerebras is benefiting from surging demand for high-speed AI inference, expanding cloud deployments and strategic partnerships with hyperscalers. Growing data center capacity, manufacturing expansion and a strong backlog are supporting its long-term growth prospects.
CBRS Benefits From Strong AI Demand and Backlog Growth
Cerebras is benefiting from robust demand for artificial intelligence (AI) infrastructure, driven by the rapid adoption of high-speed inference across enterprises, hyperscalers and AI developers. The company's second-quarter 2026 core revenues surged 103% year over year to $209.9 million, reflecting strong demand for its AI computing solutions. Core cloud and other services revenues jumped 287% to $127.7 million, supported by expanding OpenAI deployments and increased cloud customer usage. The company is aggressively expanding its data center footprint to capitalize on increasing AI infrastructure investments. The company secured more than 600 megawatts of data center capacity, either operational or under contract for delivery by the end of 2027. Its manufacturing expansion initiatives, supported by partnerships with Flex, Sanmina and TSMC, are expected to increase manufacturing capacity by more than tenfold in 2026. These investments position Cerebras to address growing customer demand and accelerate revenue growth. Strategic collaborations with OpenAI, Amazon Web Services (AWS) and other hyperscalers further strengthen Cerebras' growth prospects. Its partnership with OpenAI is supporting strong demand for high-speed AI inference, while AWS integration through Amazon Bedrock, expected to become generally available in the first quarter of 2027, should expand enterprise adoption. Growing customer engagements across AI coding, agentic workflows and cybersecurity provide additional opportunities to diversify its revenue streams. Cerebras' strong backlog also supports future upside. Remaining performance obligations stood at $25.4 billion as of June 30, 2026, supporting investments in infrastructure and manufacturing expansion. The company expects core revenues to more than triple in 2027, followed by significant growth in subsequent years. Expanding adoption across AI coding, agentic workflows and cybersecurity applications is expected to strengthen Cerebras' long-term growth trajectory.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.