Sandisk (SNDK) Stock Sees Modest Fair Value Cut As Analysts Weigh AI Demand
Sandisk’s modeled fair value has shifted from US$2,173.00 to US$2,105.29, pointing to a modestly lower price target in the latest update. This change lines u...
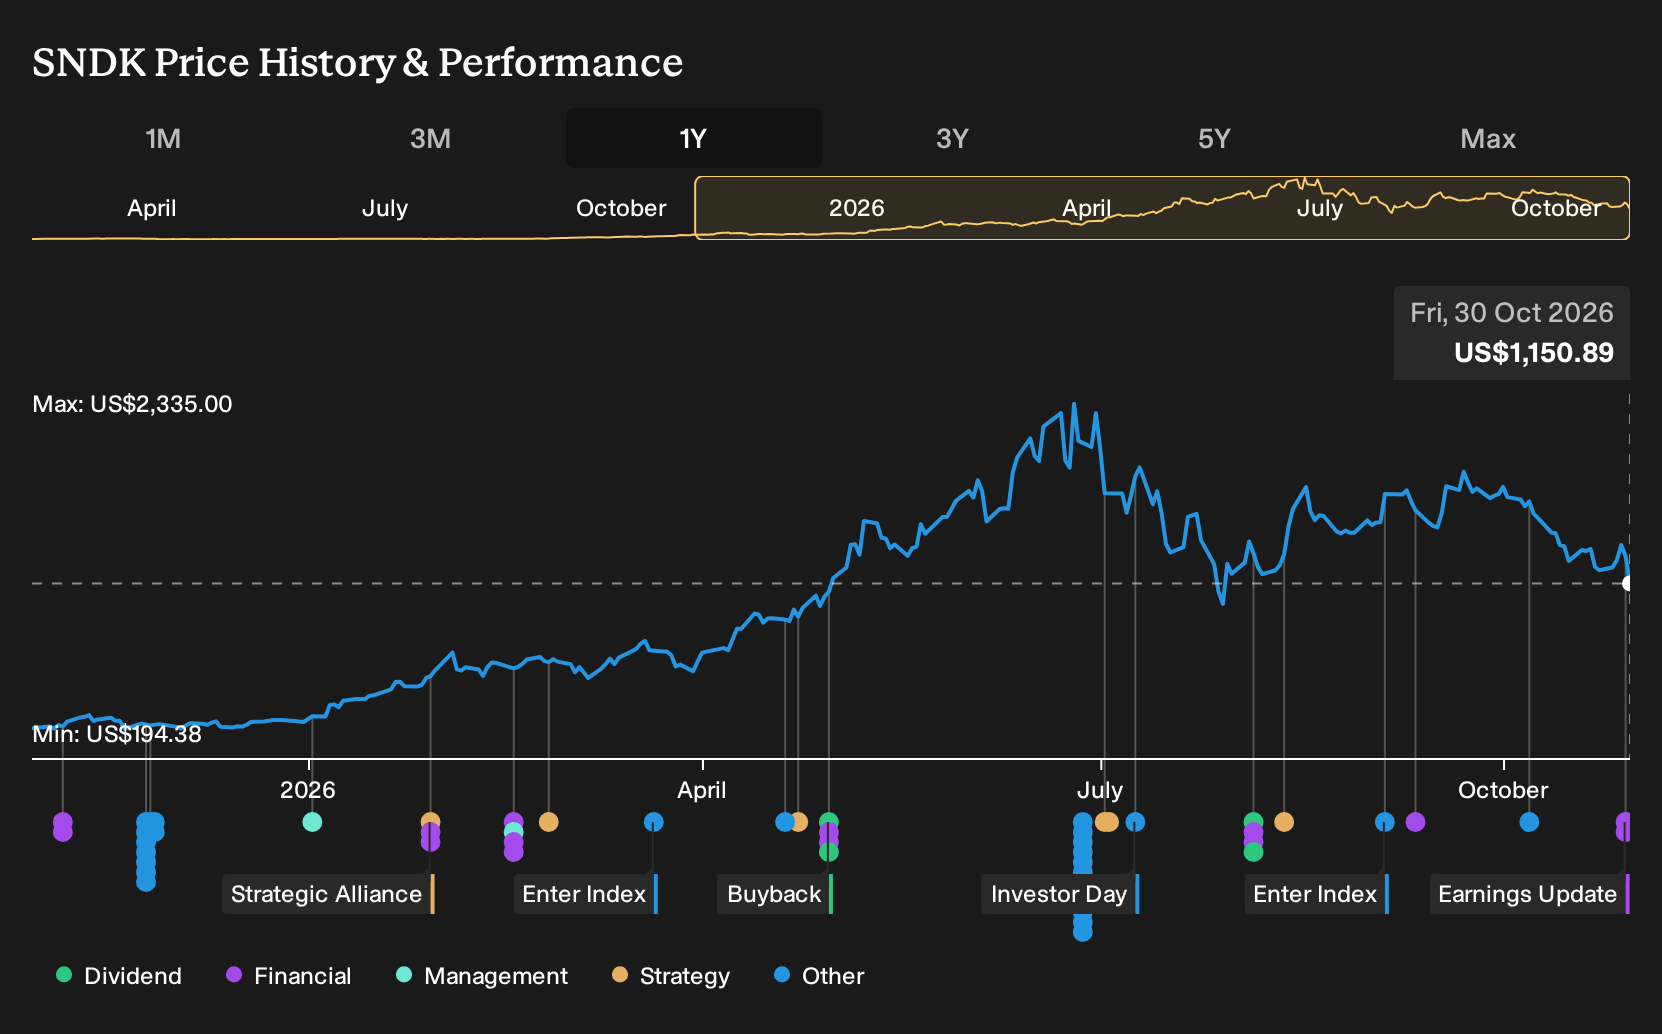
Sandisk's modeled fair value has shifted from US$2,173.00 to US$2,105.29, pointing to a modestly lower price target in the latest update. This change lines up with a mixed analyst backdrop, where enthusiasm around AI driven NAND demand and new business terms is tempered by concerns about sector multiple compression and how resilient today's conditions will be. As you read on, you will see how these moving pieces shape the evolving Sandisk story and what to watch next.
Stay updated as the Fair Value for Sandisk shifts by adding it to your watchlist or portfolio . Alternatively, explore our Community to discover new perspectives on Sandisk.
Several firms, including Evercore ISI, Mizuho, Rosenblatt, JPMorgan and Wells Fargo, highlight Sandisk as a key beneficiary of AI driven NAND demand, with Outperform or Buy ratings anchored in long term data center and enterprise storage growth themes.
Rosenblatt and Evercore point to Sandisk's technology roadmap and partnership with Kioxia as support for competitive bit cost and performance in AI oriented storage, while Evercore also emphasizes multi year demand visibility and high bandwidth flash opportunities.
JPMorgan and Wells Fargo reference the new business model framework and non bit manufacturing economics, which they see as supportive of structurally higher margins and reduced cyclicality, although they still view the valuation reset as a gradual process.
Argus cites strong reported Q4 results and momentum in data center and solid state drive solutions, and Morgan Stanley views the plan to return 100% of cash flow alongside moderate investment as a clear positive for capital allocation discipline.
RBC Capital, Citi, Jefferies and Mizuho have all trimmed Sandisk price targets over recent months, often pointing to sector multiple compression, more muted NAND pricing and questions around the durability of peak margin conditions.
Jefferies flags investor focus on moderating pricing, lower gross margin guidance and possible near term headwinds from Edge inventory builds, while Morgan Stanley is not fully convinced that industry improvements are more structural than cyclical.
Do your thoughts align with the Bull or Bear Analysts? Perhaps you think there's more to the story. Head to the Simply Wall St Community to discover more perspectives!
How This Changes the Fair Value For Sandisk
The modeled fair value for Sandisk has shifted from US$2,173.00 to US$2,105.29.
The revenue growth assumption has moved from 40.74% to 27.18%.
The net profit margin assumption has changed from 65.19% to 50.47%.
The future P/E assumption has adjusted from 11.02x to 12.21x.
The discount rate has been updated from 8.53% to 8.48%.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.