Option Traders Brace for Volatility Surge as AI Jitters Jolt Market
Accelerating US inflation and tremors across the AI sector jolted stocks in recent days, and some investors are now betting that bigger swings in tech shares...
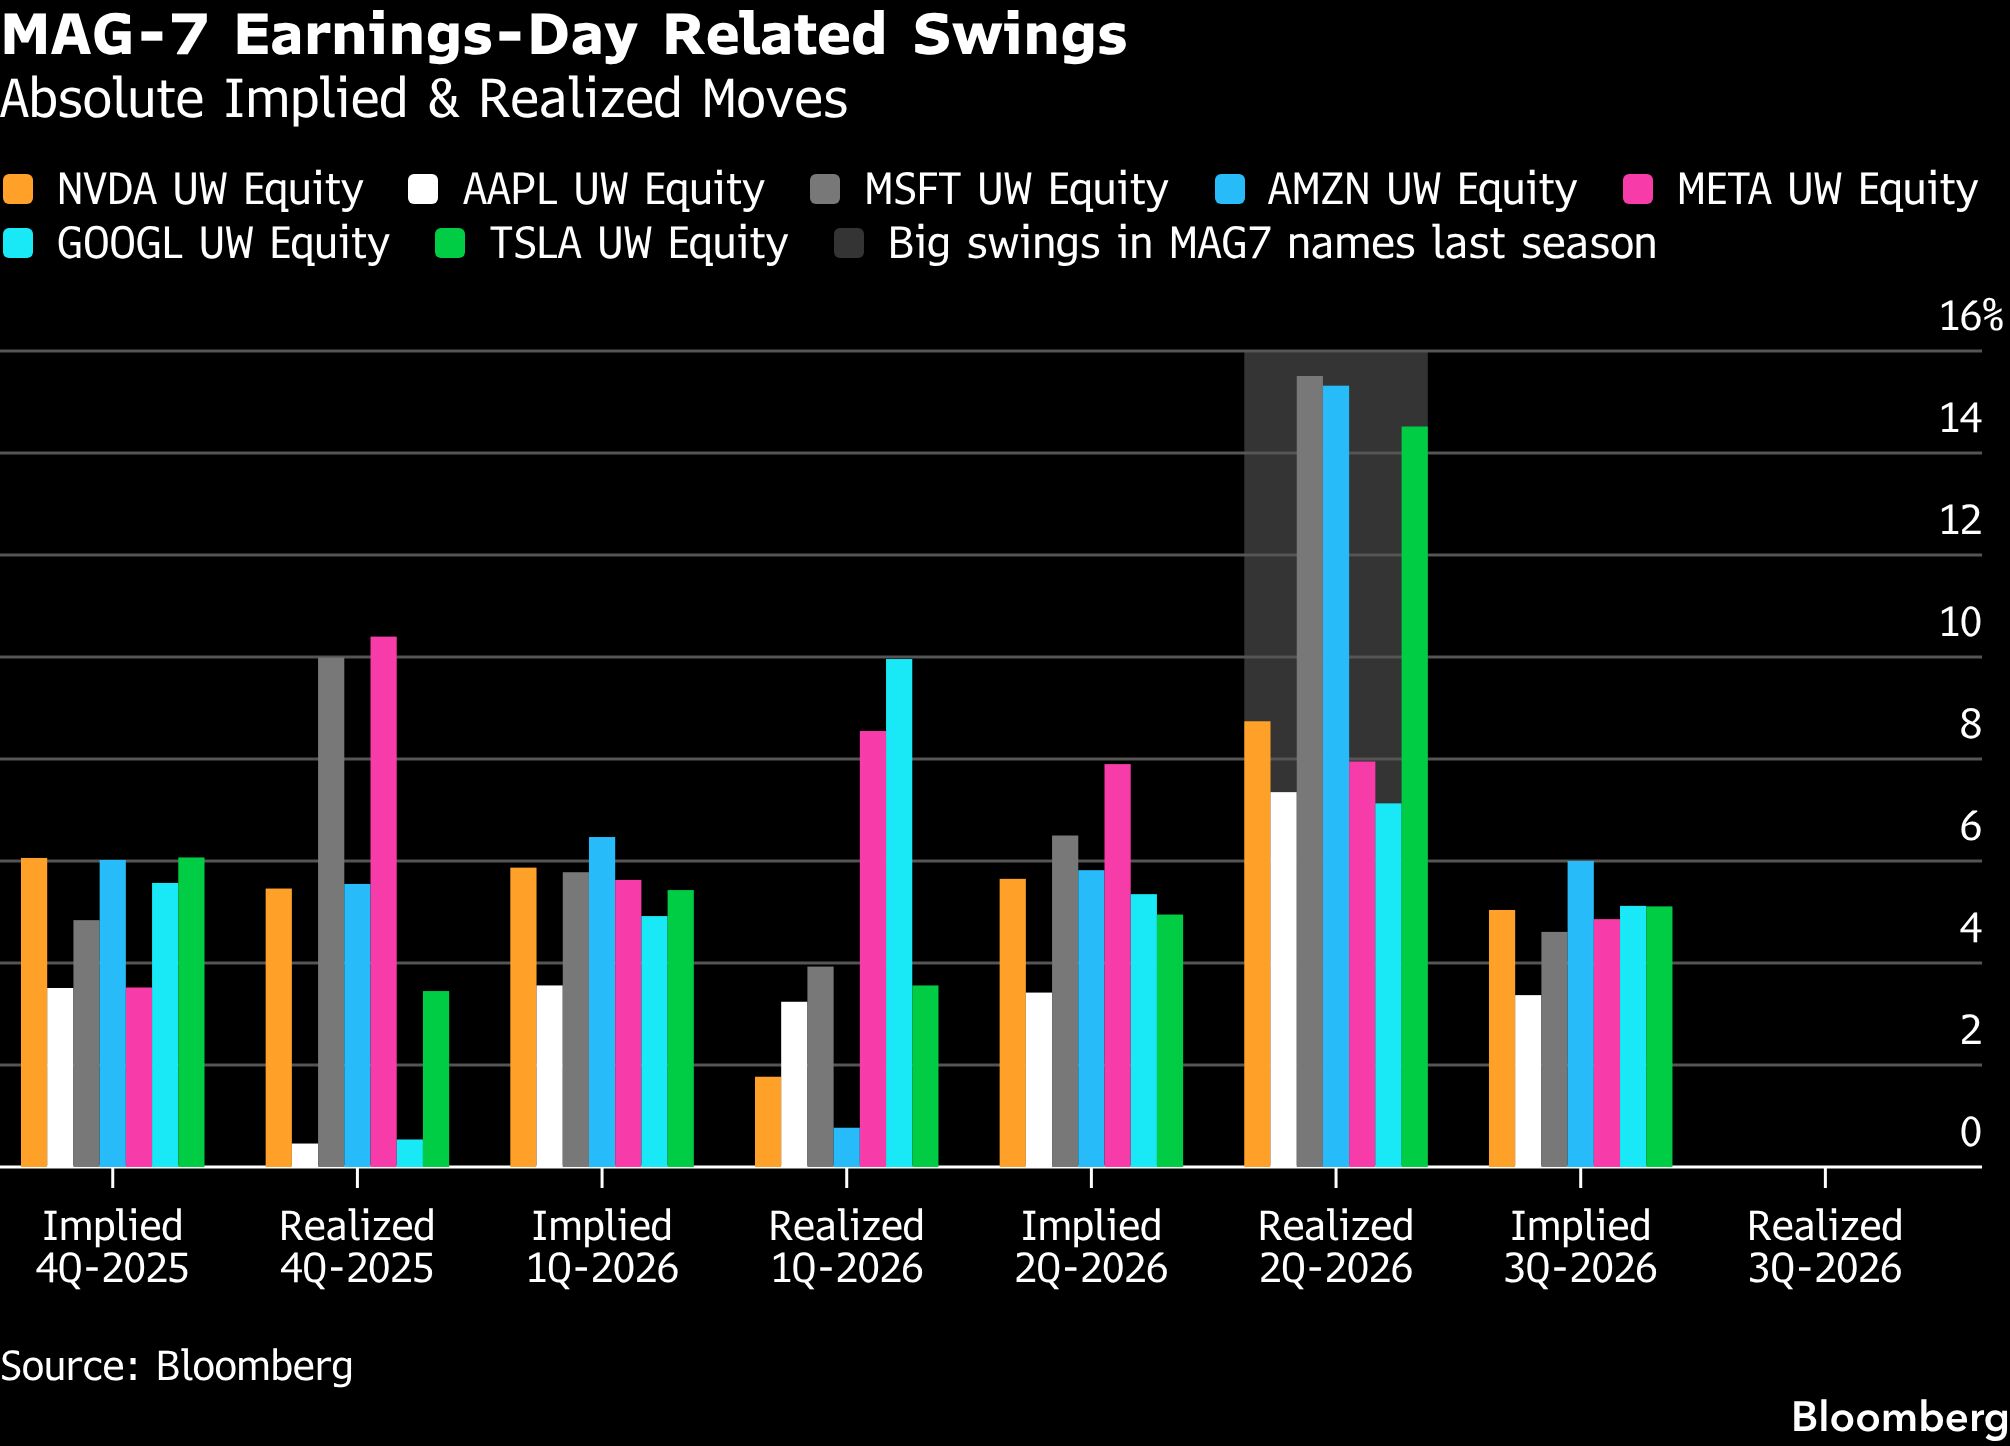
(Bloomberg) -- Accelerating US inflation and tremors across the AI sector jolted stocks in recent days, and some investors are now betting that bigger swings in tech shares will finally spread to the broader market.
Before Wednesday, the S&P 500 Index had gone 53 sessions without a 1% drop, the longest stretch since January 2020. It's not just that volatility was low, it had also been remarkably stable.
For many traders, it's becoming more a question of when rather than if the current equity rotations spill over into broader liquidation, causing volatility to spike. Despite the calm indexes, elevated Treasury yields have contributed to pockets of higher volatility among artificial-intelligence infrastructure companies and other adjacent sectors. On a macro level, persistent fuel and food inflation, driven by wars in Iran and Ukraine that show little signs of ending, adds pressure on the Federal Reserve to raise rates.
"The macro environment remains quite fragile," said Jeremy Wien, managing partner at Moo Point Capital Management. "The VIX was not pricing in nearly as much risk as I believe it should be at the moment, mostly because the SPX hasn't until Friday moved in a manner that seems to warrant it."
While Cboe Volatility Index, or VIX, call options looked like a bargain for much of the year, the minuscule swings in VIX futures paint a different picture — one where it looks expensive to hold call options betting on a spike in volatility. The vol of vol — measured with the Cboe VIX of VIX Index known as VVIX — had been sitting around the weakest level of the past two years before jumping on Friday.
Still, that hasn't deterred some investors from building long volatility positions.
Bank of America Corp. strategists recently wrote that VIX call positioning by customers has risen sharply and is approaching the levels of summer 2024, highlighting general demand for forward volatility.
One knock-on effect of customers owning the VIX calls is the potential for a volatility gamma squeeze if option dealers who are short the calls need to buy futures to re-hedge their positions. That could exacerbate a sudden VIX surge as appeared to happen on Friday, when the 6-point intraday increase in the volatility gauge exceeded the expected reaction to a nearly 1.5% drop in the S&P 500.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.