Michigan woman to dip into her $50,000 in stocks to cover her brother-in-law's unpaid HOA fees or face foreclosure
While cosigning a loan can help a loved one establish better credit, it does come with a significant amount of risk — here’s how to protect yourself.
If you've ever been asked to cosign a loan, you know that it's a major decision — and many financial experts would actually advise against it.
Why? Take Veronica, from Detroit, who called into " The Ramsey Show " after finding out her husband could be on the hook for a substantial chunk of cash after cosigning a loan for his brother.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
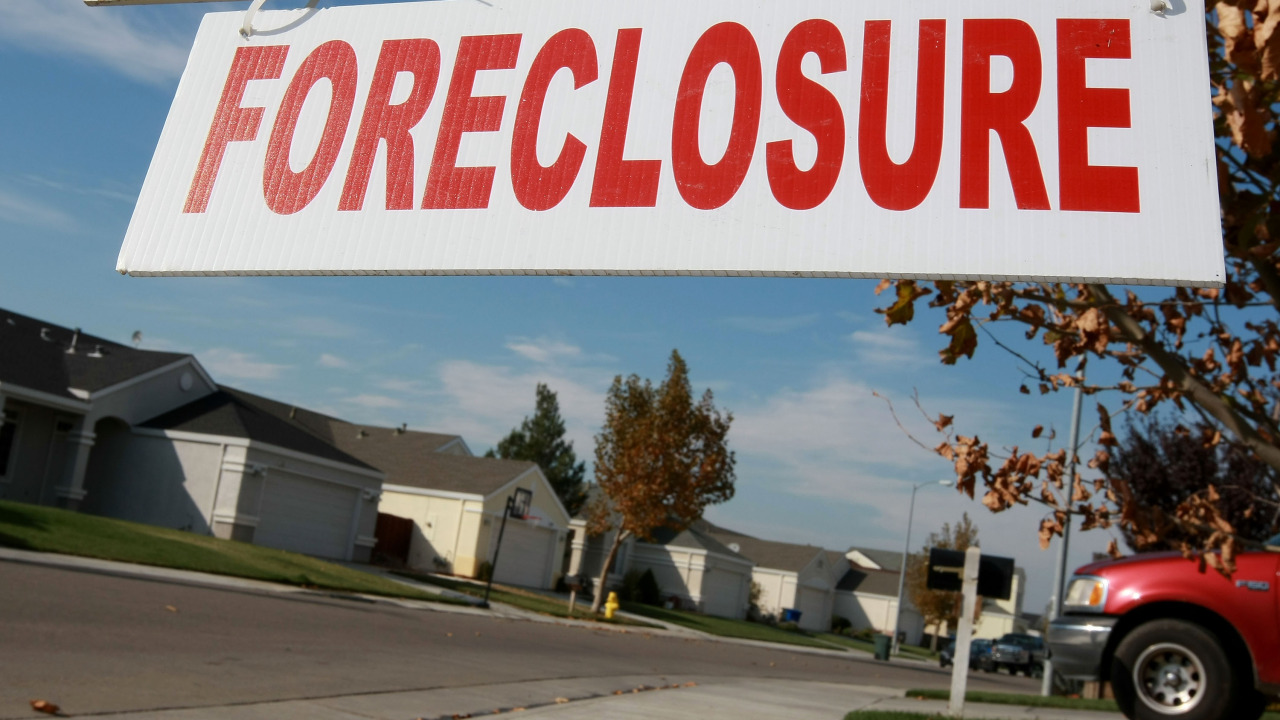
Veronica's brother-in-law asked for help buying a condo back in 2021. Since then, he's been paying the mortgage, but he stopped paying his homeowner association (HOA) fees more than a year ago. Now, Veronica's husband has been notified that he, as the cosigner, is on the hook for $10,000 in overdue fees.
And if those fees aren't paid immediately, they face foreclosure on the condo.
Veronica's brother-in-law has been trying to sell the condo. But, at the time of the call, the condo had already been sitting on the market for 81 days, even though it's priced below the original purchase price of $220,000. There's currently $172,000 left to pay on the mortgage loan.
"This is why you do not cosign," co-host Rachel Cruz told Veronica, adding later that if the bank doesn't trust the person taking out the loan, you maybe shouldn't either.
Financial hurdles have caused nearly three-quarters (74%) of prospective homebuyers to delay or reconsider buying, according to the 2026 FICO Homeownership Survey .
That could be why an increasing number of first-time homebuyers — particularly young adults — are relying on support from friends or family members. Nearly a quarter (24%) of Gen Zers and millennials who recently bought a house used family money, such as a cash gift or inheritance — to help fund their down payment, according to a Redfin survey .
Cosigning is another option, which can help those with a limited credit history (or a low credit score) qualify for a loan. But if the primary borrower defaults on the loan, it means the cosigner is on the hook.
In Veronica's case, her husband is on the hook for the $10,000 in overdue HOA fees. While they don't have enough cash on hand to pay the $10,000 outright to stall the foreclosure, Veronica does have about $50,000 in stocks sitting in a brokerage account.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.