Berkshire Hathaway (BRK.A) Formalizes Greg Abel Succession After Earnings Slip And $9.6 Billion Repurchase
Berkshire Hathaway (NYSE:BRK.A) reported weaker Q3 operating earnings as insurance results and investment income came under pressure. The group recorded a re...
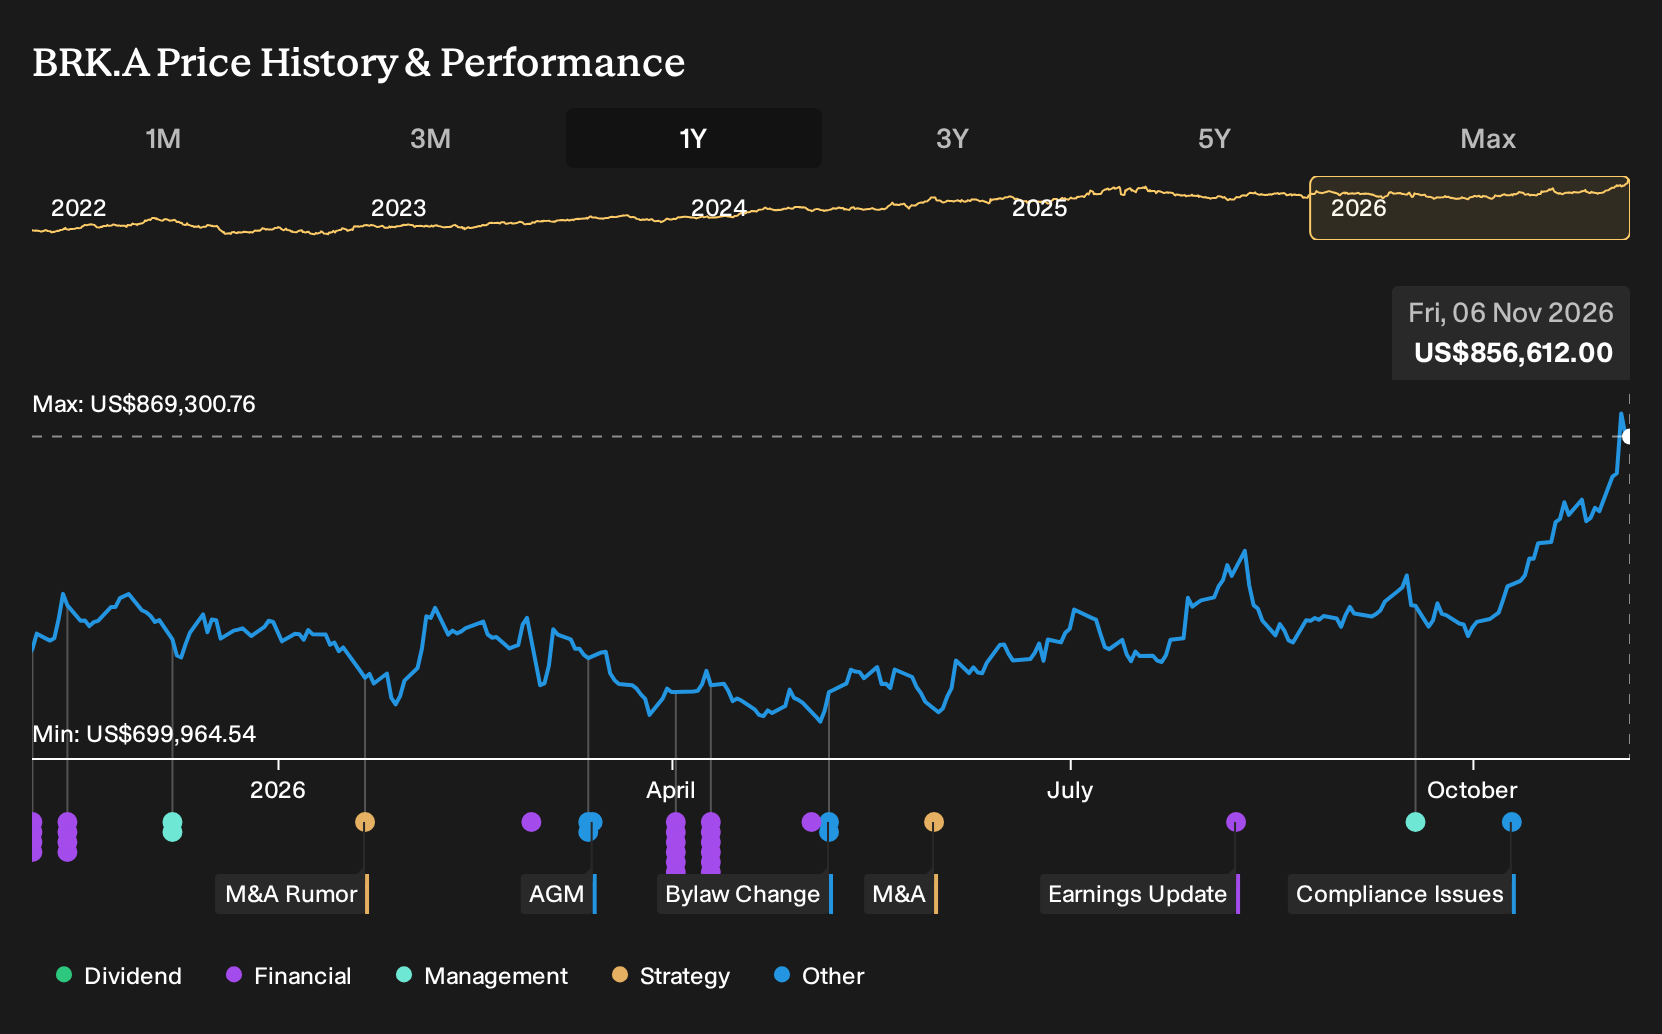
Berkshire Hathaway (NYSE:BRK.A) reported weaker Q3 operating earnings as insurance results and investment income came under pressure.
The group recorded a record US$9.6b share repurchase during the quarter, using a portion of its large cash balance.
The board formalised the leadership shift, confirming Greg Abel as Warren Buffett's successor in day to day oversight.
The combination of softer Q3 operating earnings, heavy buybacks and Greg Abel's formal step up sits alongside other trends our work has highlighted. Take a look at 3 other big wins we have identified for Berkshire Hathaway.
For readers assessing Berkshire Hathaway, it can also help to compare it with other lower-risk stocks in the same space: 29 resilient stocks with low risk scores .
Berkshire Hathaway runs a mix of insurance, freight rail and utility businesses, so shifts in underwriting results and capital allocation decisions can ripple across a wide collection of operating units that share a US$1.2t market value under one corporate umbrella.
Berkshire Hathaway's Q3 wobble as a live test of the Greg Abel Narrative
The Berkshire Hathaway Narrative rests on a simple bet that post Buffett leadership can keep the culture and capital discipline intact while a mix of insurance, utilities and long-held stakes keeps throwing off cash. This quarter's weaker insurance earnings, record buybacks and formal handover to Greg Abel all probe that assumption in real time.
"The main condition for this view is that Berkshire Hathaway's post Buffett leadership under Greg Abel and Howard Buffett maintains the existing culture, capital allocation discipline and measured approach to opportunities such as AI related power demand and global insurance expansion..."
See how the full story points towards a $799,503 fair value for Berkshire Hathaway .
The Q3 drop in operating earnings and softer insurance contribution challenge the idea that Berkshire's underwriting engine quietly carries the story on its own. At the same time, a US$9.6b repurchase against a cash pile above US$377.4b signals Abel is willing to keep shrinking the share count, which lines up with analysts expecting modest buyback led dilution over time rather than big headline deals.
Leadership formalisation is what ties this together. A more institutional decision process under Abel could mean steadier, utility and rail weighted earnings, while reducing the odds of an outsized acquisition that would reshape the profile overnight in the way some investors still associate with Warren Buffett, especially when you compare Berkshire with conglomerate style peers such as Brookfield or Markel.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.