An incentive for investment: How the US tax code can help America rebuild
Leaders in Gary, Ind., have recognized a truth facing many older American communities — that revitalization sometimes requires preserving the past, sometimes adapting it, and sometimes removing what no longer serves any productive purpose.
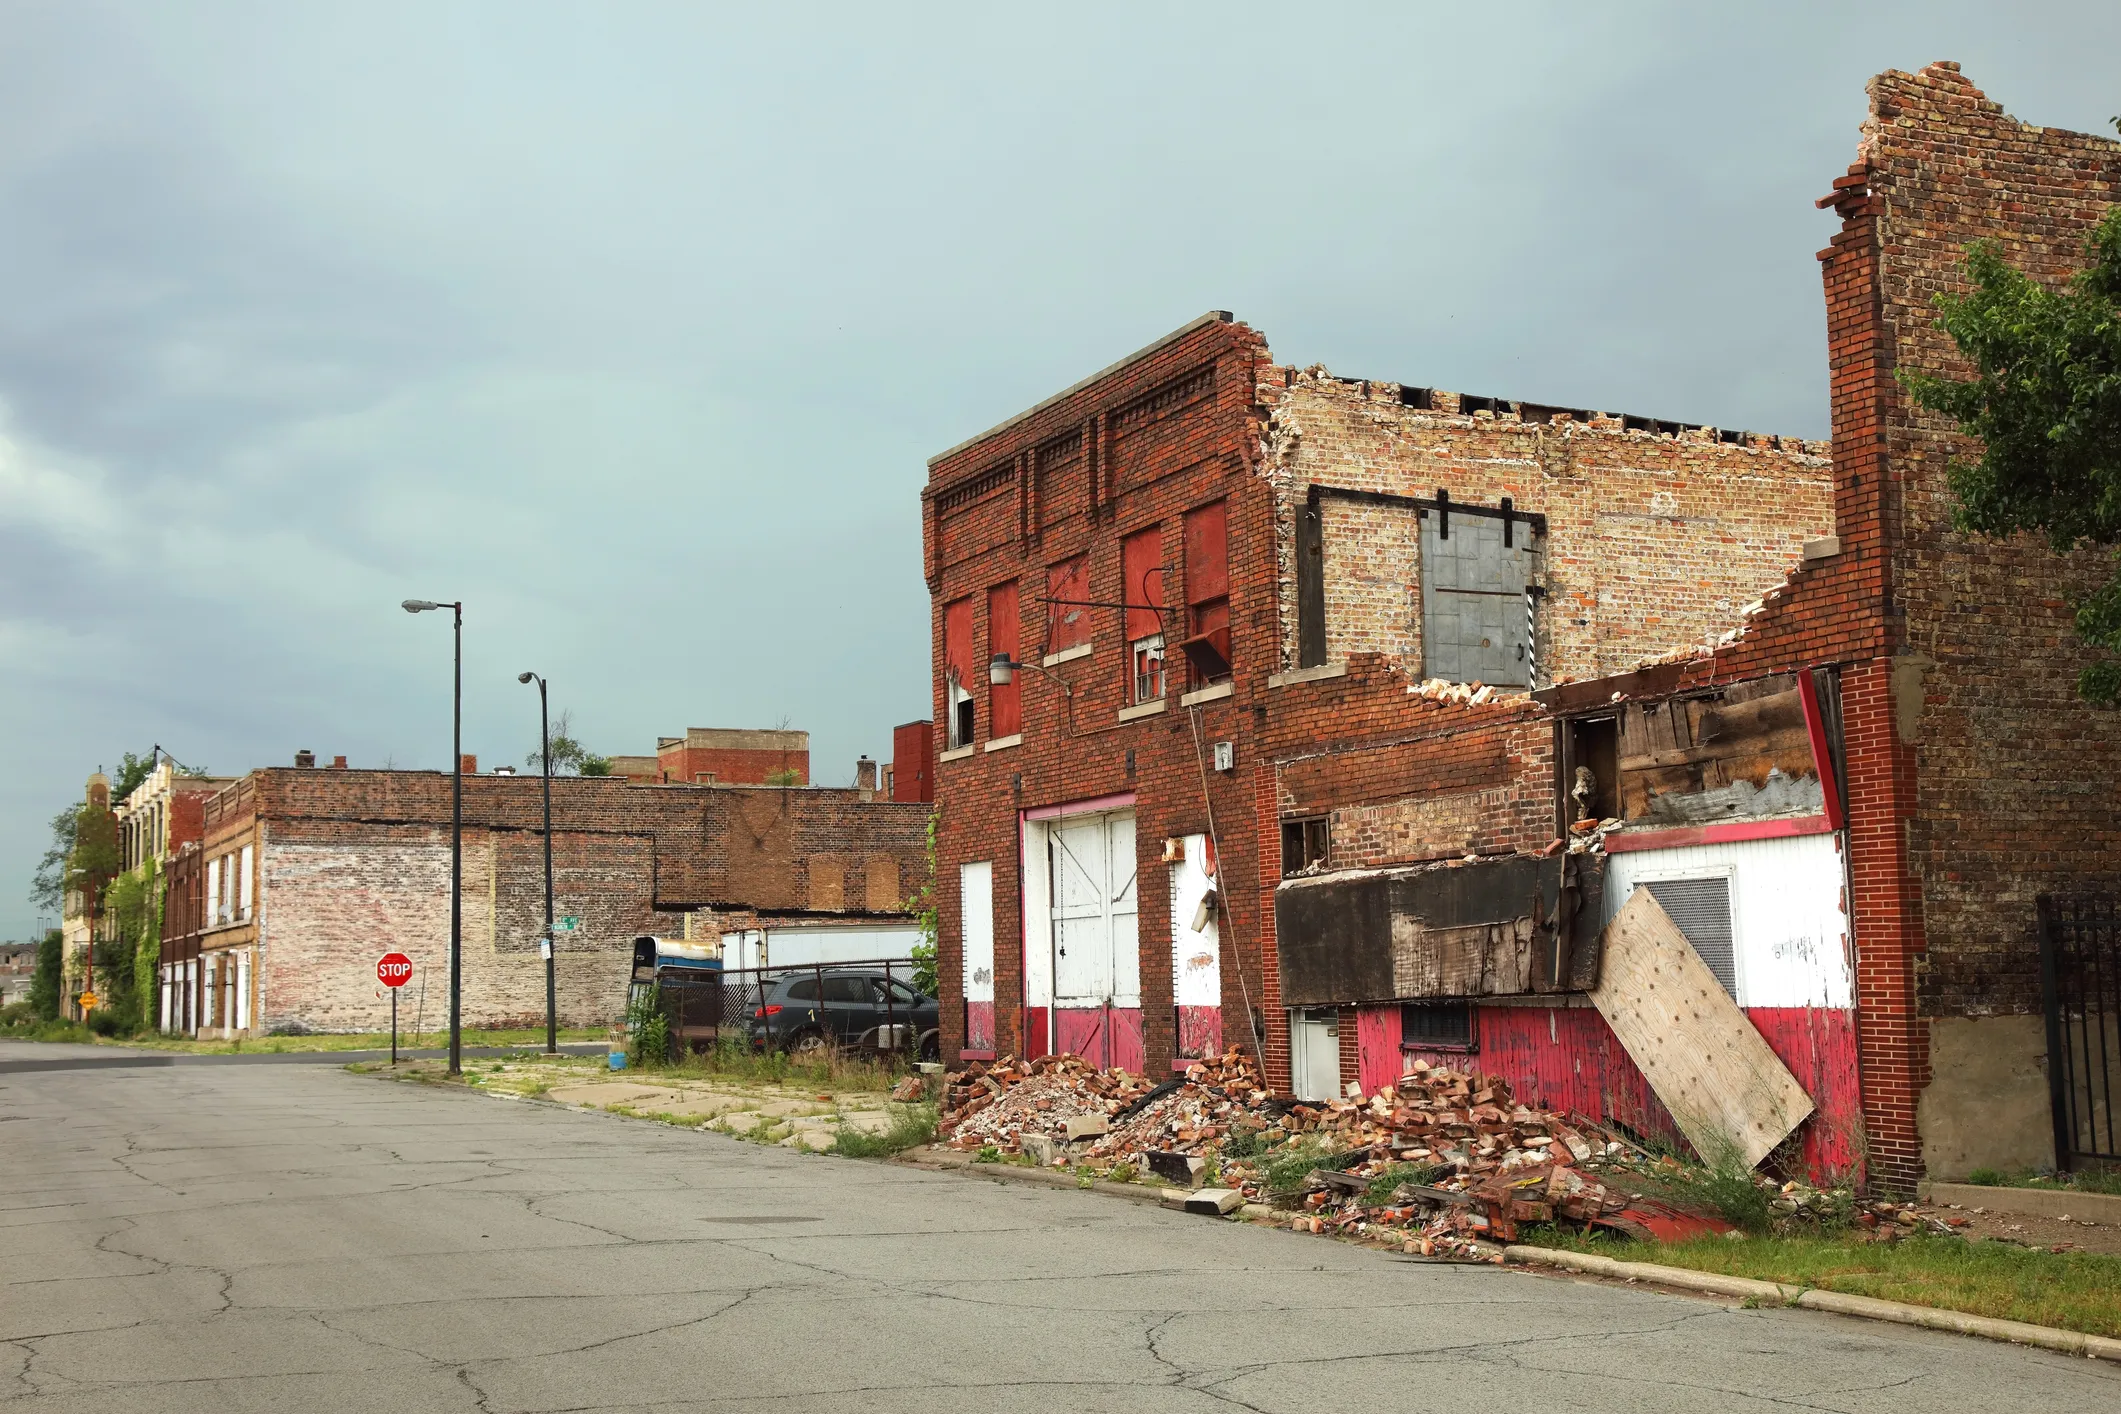
Gary, Ind., is preparing to demolish the abandoned remains of Gordon’s Department Store , once a prominent downtown destination. The implosion will be part of an $80 million campaign to remove roughly 7,000 vacant and deteriorated properties across a city that has lost more than half its population since 1960.
For many of us in real estate, partial or complete demolition is often understood as the first step toward revitalization. The city is not clearing land merely to create empty lots. It is making room for housing, offices, transportation infrastructure and private investment that cannot take hold amid blocks of unsafe and obsolete buildings.
Gary’s leaders have recognized a truth facing many older American communities — that revitalization sometimes requires preserving the past, sometimes adapting it, and sometimes removing what no longer serves any productive purpose.
Federal tax policy should support all three choices. Instead, the tax code frequently discourages the removal of obsolete buildings, provides too little assistance for preservation in deeply distressed communities, and leaves many promising commercial-to-residential conversions financially infeasible.
Under Section 280B of the tax code , when an owner demolishes a building, the cost of demolition generally cannot be deducted or depreciated. The remaining tax basis in the building cannot be claimed as a loss, either. Both amounts are added to the basis of the underlying land, which is not depreciable.
The result is economically irrational. A building may be vacant and incapable of generating income, and once demolished, it no longer exists at all. Yet the owner is unable to recover the building’s remaining basis or the cash cost of removing it until the land is sold, perhaps decades later.
The tax code effectively incentivizes economically dead buildings and disincentives removal and new investment. As Gary shows, this is a Main Street issue.
Congress should correct this distortion. An owner should be allowed to deduct the remaining basis of a demolished structure and the qualified costs of removing it. At a minimum, these amounts should be included in the depreciable basis of the replacement property rather than trapped indefinitely in non-depreciable land.
Such a policy should include reasonable safeguards, of course. Owners could be required to begin redevelopment within a fixed period, comply with a locally approved plan, and repay the benefit if the property is simply held as vacant land.
These rules would not reimburse cities such as Gary for public demolition programs. They would, however, allow private owners and developers to participate, extending scarce public dollars and making cleared sites more likely to return to productive and tax-paying use.
While Gary leaders are pursuing demolition, that is only one part of the solution. Many older buildings should be preserved rather than removed.
The bipartisan Historic Tax Credit Growth and Opportunity Act would strengthen the federal Historic Tax Credit by making it easier to use, improving its value for smaller projects and eliminating provisions that unnecessarily reduce its economic benefit. The Historic Tax Credit has already supported hundreds of billions of dollars in rehabilitation investment and millions of jobs, much of it in economically distressed areas.
Congress should also build on this legislation with a temporary enhancement for historic projects in communities facing severe economic distress. A five-year increase in credit, with a larger benefit for projects that create housing, would bring private capital into buildings while they remain physically recoverable. Eligibility should recognize the conditions that define places like Gary, including major population loss, high vacancy and persistent unemployment.
Other buildings may not retain their original purpose but can serve a new one. Empty offices, hotels, department stores and institutional buildings can sometimes be converted into housing. These projects are difficult, however. Deep floor plates, environmental conditions and local building-code requirements often create costs that ordinary residential rents cannot support, much less any degree of affordability.
The bipartisan Revitalizing Downtowns and Main Streets Act, H.R. 2410, would establish a tax credit for converting older commercial buildings into housing. That is the right concept, with modifications to ensure the credit will be substantial enough and predictable enough to change actual investment decisions.
Congress should make the credit by-right for projects that meet objective requirements. Developers, lenders and investors need to know at the beginning of a transaction whether a project qualifies.
The credit should also be temporary. A defined five-year window would control federal cost while creating urgency. It would encourage owners to act now, before buildings deteriorate beyond recovery and before today’s housing shortage becomes even harder to address .
Together, these policies would create a simple framework. Preserve buildings that can serve again. Convert those that can meet a new need. Clear those that cannot and require the land to be rebuilt. These policies would support housing production, protect historic resources and allow communities to remove dangerous properties without imposing an additional federal tax penalty.
Gary is confronting conditions that accumulated over generations. Its recovery will not happen through one demolition or one development. But the city is doing the difficult work of deciding what should remain, what should change, and what must come down.
Washington should do what it can to make those choices easier to make.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.