An Italian Wine Family Keeps Buying Oregon Vineyards as Lodi’s Grape Market Falls 50%. At 63, a Vineyard Sale Can Buy Time Before Social Security.
When a vineyard sale lands a grower a large check, the IRS sees multiple assets changing hands at different tax rates, and Social Security may not be done wi...
California's Lodi grape market sits 50% below its 2018 peak, while Italy's Marzotto family just made its fourth Oregon vineyard acquisition.
Selling a vineyard at 63 can bridge living expenses to 67, letting owners delay Social Security and gain $625 more per month.
The IRS taxes vineyard assets separately, and inventory like grapes can trigger ordinary income, so sellers can't assume all proceeds escape the earnings test.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
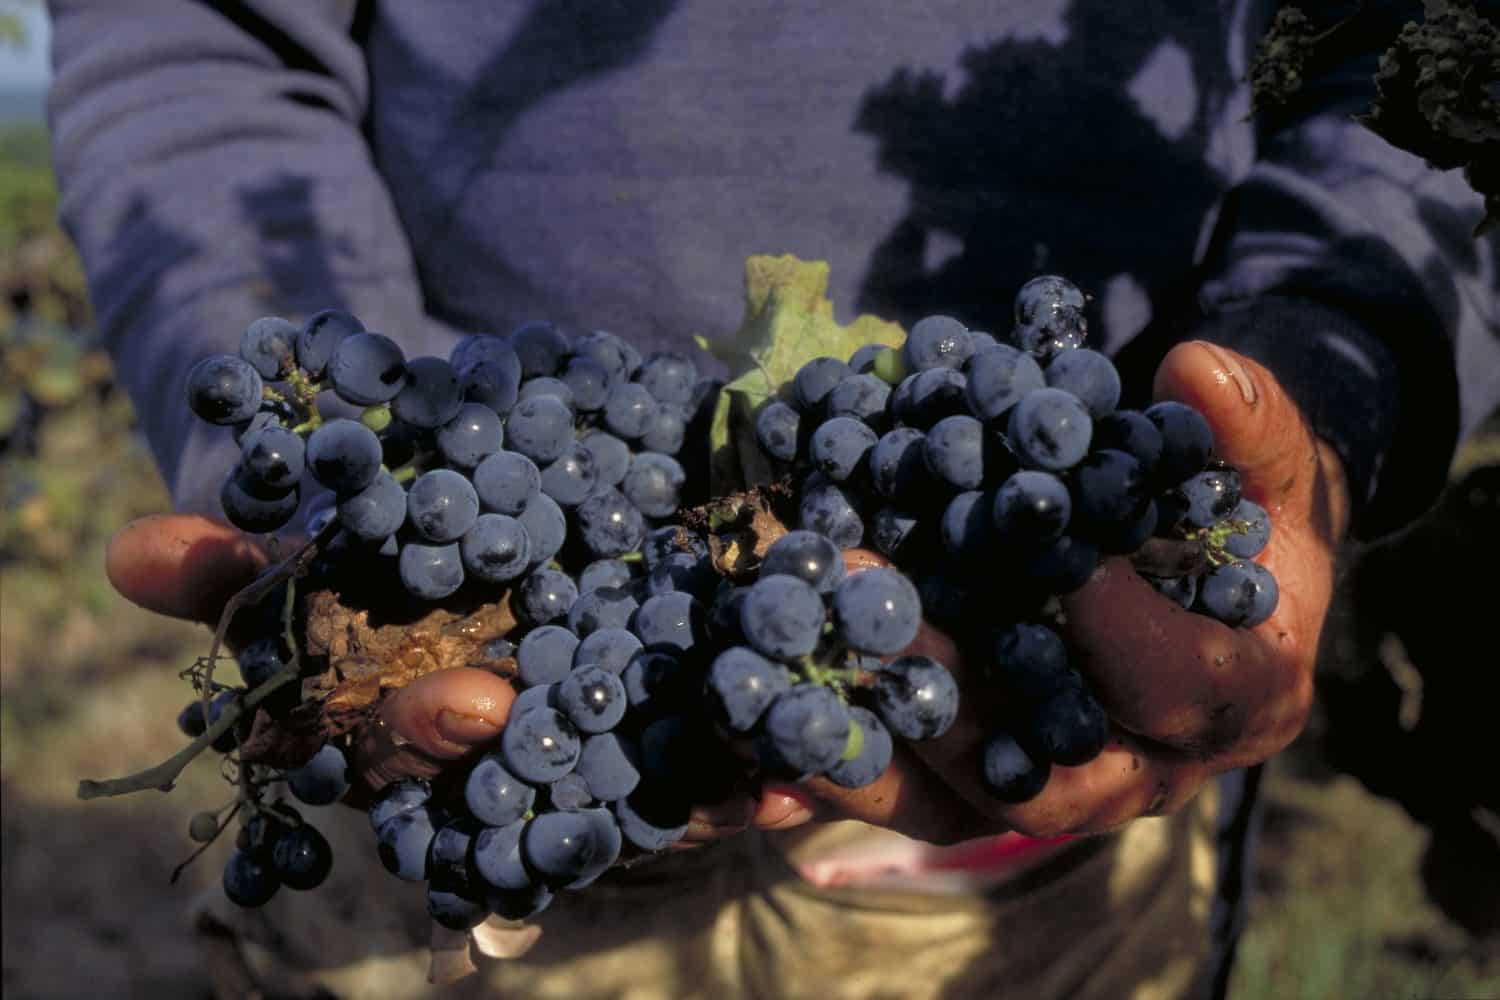
Two corners of West Coast wine country are moving in very different directions. In California's Lodi region, the grape market is now about 50% below its 2018 peak, according to industry officials, and roughly 30,000 vineyard acres have disappeared over the past decade. Growers entered the 2026 harvest with grapes still looking for buyers. Farther north, Italy's Marzotto family keeps expanding its footprint in Oregon. Herita Marzotto Wine Estates made its fourth Willamette Valley investment with the acquisition of 59 acres of Domaine Lumineux vineyards, bringing its productive holdings in the region to roughly 110 acres.
For a 63-year-old vineyard owner wondering whether this is the year to stop farming, those two trends point to the same question: if a buyer comes along, could selling the vineyard fund retirement long enough to leave Social Security alone for a few more years? It can, but the check from a vineyard sale is not nearly as simple as it looks.
For someone born in 1960 or later, full retirement age (FRA) is 67. Claiming Social Security at exactly 63 generally pays 75% of the benefit available at FRA. Someone entitled to $2,500 a month at 67 would receive roughly $1,875 if he starts four years earlier.
The 4% Rule is Broken, Built On A World That No Longer Exists
Every retiree knows about the 4% rule, but it frames retirement as a slow liquidation and still causes retirees with seven-figure accounts to agonize over a dinner out.
There's a different way to run the math that makes more sense today. Build an income floor — dividends, interest, and Social Security that cover your essential bills every month — and you never have to sell shares into a down market just to pay them.
Our free reader guide, The 4% Rule Is Broken , walks through it in about 15 minutes. Access the report here.
Topics in this story
Gathered from external sources. Rights to this text belong to whoever originally published it.